Storm Damage Roof Insurance Claim Calculator
Calculate your estimated insurance payout, factor in your wind and hail deductible, and break down replacement cost value (RCV) versus actual cash value (ACV) to navigate your storm damage claim with confidence.
Based on your inputs, this is a general planning estimate.
Illustrative comparison. Your policy determines the applicable settlement method.
Want to ensure your insurance adjuster doesn't shortchange your claim? Get a free professional roof inspection and claim review from a verified local contractor.
Enter your ZIP code to compare Licensed contractors near you.
Replacement Cost Value — generally the cost to replace the roof without deducting for depreciation.
Actual Cash Value — generally RCV minus depreciation, reflecting the roof's current condition.
An estimated reduction in value based on age and expected service life, illustrative unless insurer-specified.
The amount the homeowner pays before insurance coverage applies, either a flat amount or a percentage of Coverage A.
Under some RCV policies, depreciation may potentially be recovered after repairs are completed, subject to policy terms.
The dwelling coverage limit on a homeowners policy, often used as the basis for percentage deductibles.
An educational approximation intended to help you understand potential costs, not a guaranteed dollar amount.
Every insurance policy differs — actual coverage, depreciation, and payment depend on your specific policy and insurer.
- Estimate replacement cost (user-supplied or illustrative).
- Add selected storm-related damage.
- Apply the selected depreciation assumption.
- Calculate Actual Cash Value (ACV).
- Apply the deductible.
- Estimate the initial payment.
- Show potential recoverable depreciation under the RCV planning scenario.
- Show estimated total payment and out-of-pocket amount.
How to Use the Storm Damage Roof Insurance Claim Calculator
Our storm damage roof insurance claim calculator is designed to help homeowners understand how major claim variables can affect an estimated storm damage roof insurance claim. By entering basic information, you can explore how roof damage, repair or replacement costs, insurance deductibles, depreciation, and settlement types like ACV or RCV can interact to produce an estimated claim breakdown. You do not need every exact detail to begin, but more accurate information generally makes the estimate more useful for planning and educational purposes.
Start With the Roof and Damage Information
The calculator first needs information that helps establish the estimated repair or replacement cost for your property. This can include the roof size, roof age, roofing material, type of storm damage, repair or replacement scope, and estimated roofing costs.
The quality of the final result depends partly on the quality of the information entered. If exact measurements or professional estimates are not yet available, you can use your best reasonable estimate and update the numbers later when better documentation is at hand.
Add the Insurance Information
Next, the calculator can use insurance-related assumptions that may affect an estimated claim. These may include the policy settlement type, deductible amount, estimated depreciation, dwelling coverage when relevant, and recoverable depreciation when applicable.
Because insurance policies can differ significantly, users should look closely at their own policy documents and declarations pages whenever possible to ensure the assumptions match their actual coverage structure.
Key Information to Have Ready
Roof Size
Roof size helps establish the estimated quantity of roofing work and materials involved in the repair or replacement scope.
Roof Age
Roof age may be relevant when estimating depreciation or interpreting certain insurance settlement assumptions under your policy.
Roofing Material
Material type can affect estimated repair or replacement costs and may be relevant to standard material depreciation assumptions.
Damage Information
The type and extent of storm damage help establish the potential repair or replacement scope used in the calculation.
Insurance Details
The deductible, settlement method, and other policy information can affect the estimated claim result and final payout layout.
Use the Most Reliable Information Available
Calculator results become more useful when the inputs are based on actual roof measurements, professional roofing estimates, inspection findings, policy documents, declarations information, known deductible amounts, and insurer-provided claim information. Estimates can change when better information becomes available. You can treat the calculator as a planning and educational tool rather than a strict prediction of what an insurer will ultimately pay for a claim.
The Basic Claim Estimate Process
Enter Roof Information
Briefly explain that the user enters basic roof characteristics and storm-damage information to begin the process.
Enter Cost Information
Explain that the user enters or estimates the repair or replacement cost associated with the reported damage.
Enter Insurance Assumptions
Explain that the user provides applicable insurance assumptions such as deductible, settlement type, and depreciation when relevant.
Review the Estimate
Explain that the calculator combines the entered information to show an estimated claim breakdown clearly and concisely.
What the Calculator Results Can Show
When you run an estimate, the calculator can display several outputs that illustrate how different parts of a claim interact. You may see an estimated roof repair or replacement cost, depreciation, actual cash value, your deductible, an estimated initial insurance payment, recoverable depreciation when applicable, an estimated remaining amount, and a potential out-of-pocket amount.
Available outputs depend entirely on the calculator inputs and assumptions. The numbers are estimates intended strictly for planning and educational purposes, and they do not assume every policy uses the same settlement structure.
Understanding the Main Results
Estimated Roof Cost
This represents the estimated repair or replacement cost entered or calculated from the available roof information.
Depreciation
Depreciation can reduce an estimated value when applicable, particularly under ACV-style calculation methods.
Deductible
The deductible is the portion of a covered loss that the policyholder may be responsible for before insurance payment, subject to policy terms.
Estimated Initial Payment
Under some RCV claim structures, an initial payment may differ from the total estimated replacement cost because depreciation or other factors are applied.
Recoverable Depreciation
Some policies may allow eligible depreciation to be recovered after qualifying repairs or replacement, subject to strict policy requirements.
Estimated Remaining Cost
The result may show an amount that remains after applying modeled insurance factors, though this is an estimate and not a final out-of-pocket guarantee.
Example of How Different Inputs Can Change an Estimate
| Calculator Input | Lower Example | Higher Example | Why It Matters |
|---|---|---|---|
| Estimated roof repair/replacement cost | Lower estimated cost | Higher estimated cost | Directly impacts the baseline valuation of the project scope. |
| Roof age | Newer roof | Older roof | Influences the scale of applied physical depreciation. |
| Deductible | Lower deductible | Higher deductible | Changes the out-of-pocket portion subtracted from the payout. |
| Depreciation | Lower depreciation assumption | Higher depreciation assumption | Affects the size of the initial cash value settlement check. |
| Settlement method | ACV-style settlement | RCV-style settlement | Determines whether withheld depreciation can later be recovered. |
Why Your Estimate May Change
An estimate may change when a roofing professional provides more accurate measurements, the damage scope changes, additional damage is discovered, the deductible is confirmed, depreciation information changes, policy details are clarified, or the insurer provides its own estimate. The calculator relies entirely on the information entered and does not replace the insurer's claim evaluation or a professional roof inspection.
Before You Rely on the Result
Check the Roof Estimate
Compare the entered cost with the best available roofing estimate or inspection information to ensure proper baselines.
Check the Deductible
Use the deductible shown in the relevant policy or claim documentation when available rather than generalized averages.
Check the Settlement Type
Confirm whether the policy information being used relates to ACV, RCV, or another specialized settlement arrangement.
Check the Damage Scope
Update the estimate if a professional inspection identifies additional or different storm-related damage patterns.
Check the Policy Details
Review applicable policy information and confirm important assumptions directly with your insurance provider.
Important About the Calculator Estimate
The result is an estimate. It does not determine insurance coverage, guarantee claim approval, or guarantee an insurance payment. Actual claim results depend entirely on the specific policy language, circumstances of loss, insurer evaluation, and applicable rules. Always compare the calculator assumptions with your official policy and claim documents.
Key Takeaway
The calculator works by combining roof information, estimated damage or repair cost, and applicable insurance assumptions to produce an estimated claim breakdown. Users can improve the usefulness of the estimate by entering accurate information and updating assumptions when better documentation becomes available.
Ready to Estimate Your Storm Damage Payout?
Use the Storm Damage Roof Insurance Claim Calculator to quickly project your expected insurance payout, subtract your deductible, and view out-of-pocket costs.
Calculate Your Insurance Claim
How Storm Damage Roof Insurance Claims Are Calculated
A roof insurance claim estimate generally begins with determining the covered damage and the work needed, then estimating the cost of that work. The estimate may then be adjusted for depreciation and the policy's settlement method, followed by application of the deductible. Our calculator is designed to organize these components into an understandable estimate, helping homeowners navigate the complex sequence from initial storm damage to a finalized claim payout projection.
Start With the Roof Damage and Scope
The calculation begins with evaluating your specific roof characteristics and the storm damage sustained. This phase looks at roof size, roof type, roofing material, repair versus replacement scope, areas affected, and labor and material assumptions.
The estimated project cost calculated from these variables becomes the baseline starting point for evaluating the potential claim amount, ensuring that all necessary components of the physical repair are taken into account.
Apply the Insurance Claim Factors
Once the baseline project cost is established, it is considered alongside applicable insurance factors such as Replacement Cost Value (RCV), Actual Cash Value (ACV), depreciation, and your policy deductible.
Depending on your policy terms, this step can determine how much your initial insurance check will be, whether depreciation is recoverable after repairs are finished, and what your final out-of-pocket responsibility might look like.
The Main Parts of a Storm Damage Roof Claim Estimate
Roof Repair or Replacement Cost
The estimated cost of the covered work provides the foundation and starting point for the entire calculation.
Replacement Cost Value
RCV generally represents the estimated cost to replace damaged property without subtracting depreciation, subject to policy rules.
Depreciation
Depreciation may reduce the value used to determine an initial payment under an ACV-based calculation approach.
Deductible
The applicable deductible is generally part of the amount the policyholder is responsible for under the terms of the policy.
Settlement Method
The policy's settlement provisions determine how depreciation and other claim components are ultimately treated.
Think of the Claim Estimate as a Sequence
The calculation can be understood as a clear sequence: First, determine the covered damage and work scope. Second, estimate the cost of that work. Third, determine the applicable valuation or settlement method. Fourth, account for depreciation where applicable. Fifth, apply the policy deductible. Finally, determine what amount may be paid initially and whether additional recoverable depreciation may apply. Actual claim handling can vary significantly by policy and circumstances.
How the Claim Estimate Typically Moves From Damage to Payment
1. Determine the Covered Scope
The claim estimate starts with identifying the damage and the specific work that may be covered under your policy terms.
2. Estimate the Repair or Replacement Cost
Labor, materials, roof characteristics, and the estimated scope contribute directly to the projected project cost baseline.
3. Account for Valuation and Depreciation
The applicable settlement method may determine whether physical depreciation affects the initial claim valuation.
4. Apply the Deductible and Review the Payment
The deductible is considered, and the resulting estimate can show potential initial payments and recoverable amounts.
A Simple Way to Understand the Calculation
This is a simplified educational representation rather than a universal insurance formula. Some policies may provide replacement-cost benefits and allow eligible depreciation to be recovered after qualifying repairs or replacement are completed, subject to specific policy requirements. Not every claim follows this exact sequence.
What Can Change a Storm Damage Roof Claim Estimate?
Roof Size
A larger roof can require more material and labor, directly altering the overall cost foundation.
Roofing Material
Different materials command different replacement and labor expenses in local markets.
Damage Scope
The amount and location of damage can change the specific work included in the estimate.
Roof Age
Roof age is frequently relevant when depreciation or policy-specific settlement provisions apply.
Insurance Deductible
The applicable deductible directly affects the balance paid by the insurer versus the homeowner.
Policy Terms
Coverage limits, exclusions, endorsements, and settlement provisions shape how estimates are treated.
Example of How Claim Calculation Inputs Can Affect the Estimate
| Input | Lower Example | Higher Example | Potential Effect on the Estimate |
|---|---|---|---|
| Roof Size | Smaller roof | Larger roof | May change estimated material and labor requirements. |
| Damage Scope | Limited repair area | Larger repair or replacement scope | May change the estimated project cost baseline. |
| Roof Age | Newer roof | Older roof | May affect depreciation assumptions when applicable. |
| Roofing Material | Lower-cost material example | Higher-cost material example | May affect material and installation assumptions. |
| Deductible | Lower applicable deductible | Higher applicable deductible | May change the policyholder's share of the claim. |
How RCV, ACV, and the Initial Payment Relate
Replacement Cost Value (RCV) is generally associated with the estimated cost to replace damaged property without factoring in depreciation. In contrast, Actual Cash Value (ACV) generally reflects depreciation being considered against that replacement cost. Under many policies, a homeowner may receive an initial payment based on the applicable settlement method before repairs begin.
Under policies that provide recoverable depreciation, an additional amount may potentially become available when policy requirements and repair completion criteria are met. The deductible remains an essential part of the calculation, subtracted before final payouts are determined. Always review your actual policy language and claim documents to confirm your precise coverage terms.
Why a Calculator Cannot Guarantee an Insurance Claim Payment
A calculator can organize assumptions and demonstrate how different inputs affect an estimated claim amount, but it cannot determine whether damage is covered, whether an insurer will approve a claim, the final repair scope, the insurer's official estimate, policy-specific exclusions, whether depreciation is ultimately recoverable, or the final settlement amount. Use careful judgment and consult your insurer for binding figures.
Check These Inputs Before Interpreting the Result
Roof Cost
Make sure the estimated repair or replacement cost reflects the intended scope of work.
Roof Information
Confirm roof size, material, age, and other relevant structural characteristics.
Deductible
Use the specific deductible amount that actually applies under your policy or claim data.
Settlement Method
Understand whether the estimate is being viewed on an ACV, RCV, or other applicable basis.
Policy Details
Review applicable limits, exclusions, endorsements, and settlement provisions thoroughly.
Important About Storm Damage Insurance Claim Estimates
The calculator provides an estimate based on the information entered and should not be presented as an insurer-approved claim valuation. Actual claim outcomes depend on the insurance policy, covered damage, professional inspection findings, scope of work, applicable depreciation, deductible structure, policy limits, and other claim-specific factors.
Key Takeaway
Start with the roof damage and estimated scope, determine the estimated repair or replacement cost, consider RCV, ACV, and depreciation where applicable, apply the deductible, and review the resulting estimated payment carefully. Remember that the calculator demonstrates a calculation based on user assumptions and does not determine the final insurance settlement.
What Is RCV vs. ACV for a Roof Insurance Claim?
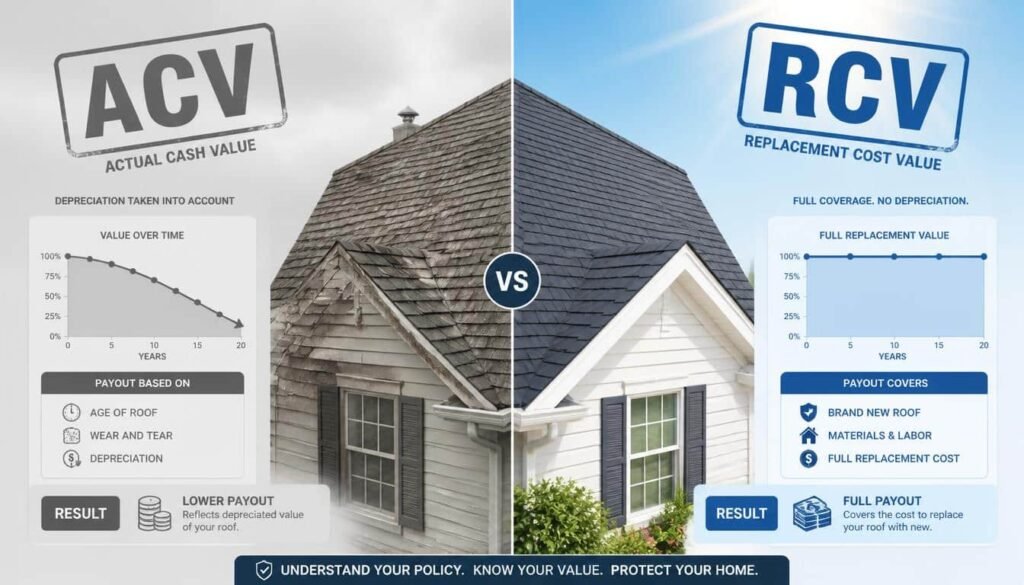
Replacement Cost Value (RCV) and Actual Cash Value (ACV) are two important valuation concepts that can appear in property insurance claims. RCV generally refers to the estimated cost to repair or replace covered damaged property without subtracting depreciation, while ACV generally takes depreciation into account when determining the value used for a payment. This distinction can affect how an insurance claim estimate is presented and how much may be paid initially. The exact settlement method is determined by the applicable policy and claim circumstances.
Replacement Cost Value (RCV)
Replacement Cost Value generally represents the estimated cost to repair or replace damaged property with materials of like kind and quality at current market prices, without deductions for physical depreciation. In a roof insurance claim, an RCV figure outlines what it would cost to restore the roof to its pre-loss condition using equivalent new materials.
However, an RCV figure does not automatically mean the insurer will pay that full amount upfront or regardless of other policy terms. It remains subject to the applicable policy deductible, coverage limits, exclusions, covered scope, and your specific settlement provisions.
Actual Cash Value (ACV)
Actual Cash Value generally takes physical depreciation into account, reflecting the estimated value of the property right before the loss occurred. Because depreciation accounts for age, wear, and condition over time, an ACV amount is typically lower than the full RCV replacement cost figure.
ACV is not simply whatever amount an insurer arbitrarily decides to pay; it is a standardized valuation calculation governed by policy terms. Under many insurance structures, an initial claim payment or valuation may be calculated on an ACV basis before any additional provisions apply.
RCV vs. ACV at a Glance
Replacement Cost Value
Estimated replacement cost before applicable depreciation is deducted.
Actual Cash Value
Value after applicable physical depreciation is taken into account.
Both terms describe valuation concepts. They do not, by themselves, determine whether a loss is covered or guarantee a particular claim payment.
Key Terms to Understand
Replacement Cost
The estimated cost to repair or replace covered property using materials of like kind and quality without age deductions.
Actual Cash Value
The valuation of damaged property that accounts for physical depreciation, age, and estimated wear over time.
Depreciation
A reduction in value associated with age, condition, wear, and other applicable factors, depending on the claim methodology.
Recoverable Depreciation
Some policies may allow certain depreciation amounts to be recovered after qualifying repairs and satisfaction of requirements.
Deductible
The portion of a covered loss that the policyholder is responsible for paying under the terms of the insurance policy.
Why RCV and ACV Can Produce Different Claim Amounts
A roof may have an estimated replacement cost based on current contractor pricing and material specifications. If physical depreciation applies to the calculation, the resulting ACV portion can be significantly lower than that initial replacement cost figure. From there, the applicable deductible is considered to determine the amount payable under the specific claim calculation structure.
If the policy includes provisions for recoverable depreciation, an additional payment may potentially become available after qualifying work is completed and policy requirements are satisfied. This interaction shows why a single valuation figure does not tell the whole story of a claim payout. This is a simplified explanation, and actual claim handling varies across different providers and policy forms.
How RCV and ACV Can Appear in a Claim Estimate
Where a policy provides recoverable depreciation, an additional eligible amount may potentially be paid later when applicable requirements are met. This is an educational illustration only and is not a universal formula.
RCV vs. ACV: What Each Term Means
| Feature | RCV | ACV |
|---|---|---|
| Basic meaning | Estimated replacement cost | Value after applicable depreciation |
| Depreciation | Generally not subtracted from the RCV figure | Generally considered in determining ACV |
| Relationship to replacement | Focuses on the estimated cost to replace or repair | Reflects the property's value after applicable depreciation |
| Potential payment timing | May be used to establish the replacement-cost portion of a claim | May be used to determine an initial or actual-cash-value payment |
| Recoverable depreciation | May exist when the policy provides for it | May represent an amount potentially recoverable under policy terms |
| Deductible | May still apply | May still apply |
| Policy dependence | Yes | Yes |
Why an RCV Estimate Does Not Automatically Equal the Final Insurance Payment
An RCV figure is only one component of a comprehensive claim evaluation. Other factors that shape the final outcome include the covered scope of damage, policy limits, deductibles, exclusions, endorsements, applicable depreciation schedules, settlement provisions, required documentation, and repair completion requirements. Homeowners should not assume that an initial RCV estimate represents the exact net amount that will be delivered by the insurer. Reviewing official documentation helps clarify how these various pieces fit together under your specific agreement.
What Can Affect the Difference Between RCV and ACV?
Roof Age
Older property may have more physical depreciation applied under an applicable valuation method.
Roof Condition
Prior condition can be relevant to depreciation or valuation depending on policy terms and claim methodology.
Roofing Material
The material characteristics and expected service life may influence the overall valuation process.
Claim Settlement Terms
Specific policy provisions dictate precisely how valuation and depreciation are managed.
Recoverability Rules
Certain policies allow eligible depreciation to be recovered when specified milestone requirements are met.
What Is Recoverable Depreciation?
A claim estimate may display a full replacement-cost figure alongside a calculated amount of physical depreciation. Under many replacement-cost policies, part of that depreciation may be initially withheld by the insurer and potentially paid out later after the policyholder completes qualifying repairs or replacement and satisfies all applicable insurer requirements.
Recoverable depreciation is not automatically available on every insurance policy or every storm damage claim. Specific deadlines, contractor invoicing documents, proof of repair completion, and policy endorsements frequently govern whether these funds can be unlocked. Understanding this mechanism helps explain why initial settlement checks may differ substantially from the total projected replacement cost.
Three Ways a Roof Claim May Be Presented
Replacement-Cost Estimate
The estimate may display the projected full replacement cost before applicable physical depreciation is subtracted.
Actual-Cash-Value Estimate
The estimate may emphasize a valuation derived after applicable physical depreciation and wear have been factored in.
RCV With Recoverable Depreciation
An initial payment may be based on initial calculations, with an additional eligible amount potentially available later.
What to Check in Your Insurance Policy
- Does the policy use replacement cost or actual cash value for the roof?
- How does the policy address physical depreciation and service life?
- Is withheld depreciation potentially recoverable after repairs?
- What specific deductible amount applies to the loss?
- Are there roof-specific limitations, exclusions, or endorsements?
- Are there conditions or milestones that must be met before depreciation can be recovered?
- Are there strict filing deadlines or documentation requirements?
The wording in the actual policy controls. Educational tools can help explain the numbers, but they cannot replace review of official policy or claim documents.
Important About RCV and ACV
RCV and ACV are useful concepts for understanding a roof insurance claim estimate, but the terms alone do not determine coverage or the final settlement. The actual result depends on the insurance policy, covered damage, roof characteristics, claim scope, deductible rules, depreciation provisions, limits, exclusions, endorsements, and other claim-specific circumstances.
Key Takeaway
Replacement Cost Value generally represents the estimated replacement cost before applicable depreciation, while Actual Cash Value accounts for physical depreciation. This distinction can alter initial claim valuations, and some policies allow eligible depreciation to be recovered later. Ultimately, the deductible, policy terms, and official documents determine how these valuation concepts apply to your claim.
Ready to Estimate Your Storm Damage Payout?
Use the Storm Damage Roof Insurance Claim Calculator to quickly project your expected insurance payout, subtract your deductible, and view out-of-pocket costs.
Calculate Your Insurance ClaimHow Roof Depreciation Affects a Storm Damage Insurance Claim
Depreciation is an adjustment that may appear in a property insurance claim estimate to account for age, condition, wear, or other valuation considerations. When a roof is damaged by a covered storm event, the estimate may show both a replacement-cost amount and depreciation. This depreciation can affect the amount used for an initial payment, depending on the policy's settlement method. Recoverable depreciation may also play a role when certain conditions are met. Depreciation is not the same thing as storm damage, and treatment varies by policy.
What Is Roof Depreciation?
Depreciation reflects the reduction in value associated with factors such as age, wear, condition, and expected useful life when those factors are relevant under the applicable claim valuation method. It is important to understand that depreciation is a valuation concept, not an additional repair cost, and not the same thing as the amount of physical damage.
The presence of depreciation on an estimate does not automatically mean a claim is denied or that the roof was poorly maintained. The way depreciation is calculated depends strictly on the policy terms and specific claim circumstances.
Why Does Depreciation Appear on a Claim Estimate?
An estimate may list depreciation separately so that the reader can see the estimated replacement cost, applicable depreciation, adjusted value, potential initial payment, and any potential recoverable amount where applicable. Separating these figures helps clarify how the valuation was derived.
However, the presence of a depreciation line item does not by itself tell the homeowner what the final claim payment will be. It is simply one component of the broader claim calculation structure.
What Can Be Relevant to Roof Depreciation?
Roof Age
The age of the roof may be considered when depreciation is determined, depending on the policy and valuation method.
Roof Condition
Prior condition and wear can be relevant to property valuation under the applicable claim rules.
Roofing Material
Different roofing materials can have distinct characteristics and expected service lives.
Valuation Method
The policy's settlement provisions determine how depreciation is factored into the claim.
Policy Terms
The actual policy controls applicable depreciation provisions, limits, exclusions, and related requirements.
Depreciation Is Not the Same as Roof Damage
Physical damage refers to the actual harm caused to the structure by the covered storm event, such as missing shingles, punctured membranes, or impact marks. Depreciation, on the other hand, is a valuation adjustment that may account for age, condition, wear, or other applicable factors over time.
A roof can sustain severe physical storm damage while also having depreciation reflected in its overall financial valuation. Depreciation does not measure how intense the storm was or how much physical destruction occurred; it is purely part of the valuation methodology used in the claim estimate.
How Depreciation Can Affect a Roof Claim Estimate
This is a simplified educational representation. Actual claim calculations can differ depending on the policy, settlement method, covered scope, and claim-specific circumstances. Where recoverable depreciation is available, an eligible amount may potentially be paid later after applicable requirements are met.
How Depreciation Can Affect the Claim
Estimated RCV
The estimate may begin with the projected replacement cost of the covered work.
Depreciation Amount
An applicable depreciation amount may be shown separately to reflect valuation adjustments.
ACV Amount
Depreciation may reduce the value used for an ACV-based calculation approach.
Initial Payment
The initial payment may be lower than the replacement-cost figure when depreciation is withheld.
Recoverable Depreciation
Some policies may allow eligible depreciation to be recovered after qualifying criteria are met.
Final Claim Amount
The final amount depends on the policy, covered scope, deductible, and claim requirements.
What Is Recoverable Depreciation?
Some replacement-cost policies may include provisions for recoverable depreciation. Under this setup, a claim estimate may initially withhold part of the calculated depreciation. After qualifying repairs or replacement are completed, the policy may allow some or all of the eligible withheld depreciation to be recovered by the policyholder.
Requirements to unlock these funds can include proper documentation, proof of completed work, adherence to deadlines, or other specific policy conditions. It is important to note that not every policy provides recoverable depreciation, not every depreciation amount is necessarily recoverable, and the governing policy language and claim documents always control.
Roof Depreciation: What Different Claim Terms Mean
| Term | What It Represents | Why It Matters |
|---|---|---|
| Replacement Cost | Estimated cost to repair or replace the covered property | Provides a reference point for the replacement-cost portion of the estimate |
| Depreciation | Applicable reduction in value based on age, condition, or wear | May reduce the amount used for an ACV calculation |
| Actual Cash Value | Value after applicable depreciation is considered | May influence an initial claim payment amount |
| Recoverable Depreciation | Eligible depreciation that may potentially be paid later under policy terms | Can affect the total amount ultimately paid when requirements are satisfied |
| Deductible | The policyholder's applicable share of a covered loss | Can reduce the amount payable under the claim calculation |
What Roof Depreciation Does Not Automatically Mean
Not a Denial
It does not mean the damage is not covered under the terms of the policy.
Not a Question of Harm
It does not mean the roof did not experience real physical storm damage.
Not a Final Verdict
It does not guarantee a claim denial or dictate the final claim payout on its own.
Not a Single Outcome
It does not automatically determine the final settlement amount without other factors.
Not a Universal Formula
It does not follow a single formula across every insurance company and policy.
Why Roof Age Matters — But Does Not Tell the Whole Story
Roof age can be relevant when determining depreciation, but age is only one potential consideration in a property valuation. Other factors that can influence the assessment include the specific roofing material, overall maintenance condition, wear and tear, existing pre-loss wear, the applicable valuation method, and the governing policy language.
Homeowners should avoid assuming a specific depreciation percentage simply based on the chronological age of the roof. Because calculation methods and policy endorsements vary widely, official claim documentation and policy terms provide the only reliable guide to how depreciation is applied in a given situation.
How the Same Roof Cost Can Lead to Different Valuations
Lower Depreciation Assumption
A newer or differently valued roof may have a smaller applicable depreciation amount under the relevant methodology.
Higher Depreciation Assumption
An older or differently valued roof may have a larger applicable depreciation amount under the relevant methodology.
Recoverable Depreciation
If the policy allows recoverable depreciation and conditions are met, an eligible withheld amount may potentially be paid later.
Questions to Ask When You See Depreciation on a Roof Claim Estimate
- What replacement-cost amount is shown on the estimate summary?
- What exact depreciation amount is listed for the roofing materials and labor?
- Is the listed depreciation recoverable under the terms of the policy?
- What specific valuation method applies to the roof under the policy?
- What deductible amount applies to the overall claim?
- What specific requirements or milestones must be met to recover eligible depreciation?
- Are there strict deadlines for submitting proof of completed work?
- Does the estimate clearly identify the roof scope being evaluated?
Use the actual policy and claim documents to verify how depreciation applies to your specific claim.
Important About Roof Depreciation
Depreciation is one component of an insurance claim estimate and should not be interpreted in isolation. The amount and treatment of depreciation can depend on policy terms, settlement methods, roof age, roof condition, roofing material, claim scope, applicable limits and exclusions, and requirements for recoverable depreciation. Educational tools can illustrate how depreciation affects an estimate, but they cannot determine the depreciation amount an insurer will use for a specific claim.
Key Takeaway
Roof depreciation is a valuation concept that may reduce the value used in an ACV-based calculation. While roof age and condition can be relevant, they are not the only factors. Some policies allow eligible depreciation to be recovered after meeting specific criteria, but the deductible, policy provisions, and official claim documents ultimately determine how depreciation applies.
How Roof Insurance Deductibles Affect Your Claim
A deductible is generally the portion of a covered loss that the policyholder is responsible for under the policy. After the applicable claim value is determined, the deductible can affect the amount considered payable by the insurer. Deductibles can be structured in different ways, including flat-dollar and percentage-based deductibles, depending on the policy terms. The actual policy controls which deductible applies and how it is calculated for a specific claim.
What Is an Insurance Deductible?
The deductible represents an amount or applicable share of a covered loss that the policyholder is responsible for under the policy before the insurer pays the remaining covered amount, subject to policy terms. It is entirely different from depreciation, distinct from the estimated repair cost, and separate from any policy limit.
A deductible does not determine whether damage is covered; rather, it is a financial factor applied after coverage and valuation are established. The applicable deductible depends strictly on the governing policy and specific claim circumstances.
Why Does the Deductible Matter for a Roof Claim?
The deductible can directly reduce the amount payable by the insurer after the covered claim value is established. Because of this, a homeowner may see a roof estimate listing a substantial repair or replacement cost while the estimated insurance payment is lower once the applicable deductible and other claim adjustments are considered.
Understanding how the deductible fits into the calculation helps clarify why estimated initial payments or claim payouts differ from the total gross estimate of the roof work.
Where the Deductible Fits Into a Roof Claim Estimate
This is a simplified educational representation. Actual claim calculations can vary depending on policy terms, settlement method, covered scope, limits, exclusions, and other claim-specific factors.
Common Deductible Structures to Understand
Flat-Dollar Deductible
Some policies specify a fixed dollar amount that applies to a covered loss.
Percentage Deductible
Some policies may express certain deductibles as a percentage of a policy-defined amount or limit.
Wind or Hail Deductible
Some policies may contain a separate deductible that applies to specified wind or hail losses.
Hurricane / Storm
Some policies in certain locations may contain special deductibles for particular storm events.
Policy-Specific
The deductible shown in the actual policy and claim documents is what should be used.
Flat-Dollar vs. Percentage Deductibles
A flat-dollar deductible is a specified, fixed dollar amount outlined in the policy. A percentage deductible, by contrast, is generally based on a percentage of a policy-defined amount or limit, such as the dwelling coverage limit rather than the cost of the roof repair itself.
Homeowners should be careful not to automatically calculate a percentage deductible directly from the roofing contractor's estimate unless the policy specifically defines that the percentage is applied to that basis. Verifying the policy wording ensures accurate understanding.
Roof Insurance Deductible Types at a Glance
| Deductible Type | How It Is Generally Expressed | What to Check |
|---|---|---|
| Flat-Dollar | A fixed dollar amount | The exact deductible stated in the policy or claim documents |
| Percentage | A percentage applied according to the policy's defined basis | What specific amount or limit the percentage is applied to |
| Wind/Hail | A deductible associated with specified wind or hail losses when included | Whether it applies to the specific loss event under review |
| Hurricane/Named Storm | A special deductible that may apply to specified storm events | The policy definition of the triggering storm event |
| Other Policy-Specific | A deductible or structure defined by individual policy provisions | The applicable policy wording and attached endorsements |
Deductible vs. Depreciation: They Are Not the Same
Deductible
The deductible is generally the policyholder's applicable share of a covered loss, representing the out-of-pocket portion defined by the policy terms before insurance proceeds apply.
Depreciation
Depreciation is a valuation adjustment that may account for age, condition, wear, or other applicable factors to reflect the current condition of materials within the claim estimate.
Both can affect an estimated insurance payment, but they represent entirely different parts of the claim calculation.
What Can Affect Which Deductible Applies?
Cause of Loss
The policy may define different deductibles for different covered causes of damage.
Storm Type
Certain policies may contain special provisions or triggers for particular storm events.
Property Location
Deductible structures and requirements can vary by policy and regional risk guidelines.
Policy Endorsements
Attached endorsements can modify or add specific provisions affecting deductibles.
Claim Circumstances
The applicable deductible depends on the specific loss being evaluated under the policy.
Policy Wording
The actual policy declarations and claim documents should always be verified.
Why the Deductible in a Calculator Must Match the Policy
Educational calculators can demonstrate how different deductible assumptions change an estimated payment, but entering an incorrect deductible can make the output misleading. It is important to verify the exact deductible amount, deductible type, cause-of-loss provisions, wind and hail clauses, storm-specific provisions, applicable endorsements, and the policy-defined basis for percentage deductibles.
The deductible figure should always come directly from the actual insurance policy or official claim documentation rather than being guessed or assumed from a general contractor's roof estimate.
How Different Deductible Structures Can Change an Estimate
Fixed Deductible
A fixed deductible subtracts a specified, set dollar amount from the covered claim calculation when applicable.
Percentage Deductible
A percentage deductible may produce a distinct dollar total depending on the policy-defined basis used for the math.
Special Storm Deductible
A policy may specify a different deductible structure for certain storm-related losses based on policy language.
Do Not Assume the Roof Estimate Determines the Deductible
The deductible is determined exclusively by the applicable policy provisions and is not necessarily calculated as a percentage of the roofing contractor's estimate. As noted, a percentage deductible is frequently tied to a separate policy-defined amount, such as the overall dwelling limit. Making this distinction clear prevents common misunderstandings when reviewing estimated paperwork.
Before Using a Deductible in a Claim Estimate
- Confirm the exact deductible amount or percentage stated in the paperwork.
- Confirm whether it is structured as a flat-dollar or percentage deductible.
- Check what specific policy-defined amount a percentage deductible applies to.
- Check whether a separate wind or hail deductible applies to the roof.
- Check whether a storm-specific or named-storm deductible applies.
- Review any relevant policy endorsements that modify standard terms.
- Confirm the applicable cause of loss being evaluated.
- Use the deductible shown in the actual policy or official claim documents.
If the policy language is unclear, educational estimators should not be treated as a substitute for reviewing actual policy documents.
Important About Roof Insurance Deductibles
The deductible is only one component of a roof insurance claim calculation. Other influencing factors include covered damage, repair or replacement scope, replacement cost or actual cash value treatment, depreciation, policy limits, exclusions, endorsements, and claim-specific requirements. Calculators can illustrate the effect of a deductible on an estimate, but they cannot determine which deductible legally or contractually applies to a specific insurance claim.
Key Takeaway
A deductible is generally the policyholder's applicable share of a covered loss and can reduce the amount considered payable by the insurer. Deductibles may be flat-dollar or percentage-based, and some policies include specialized wind, hail, or storm deductibles. Because the deductible differs entirely from depreciation, the actual policy and official claim documents ultimately determine which deductible applies and how it is calculated.
What Types of Storm Damage Can Affect a Roof Insurance Claim?
Storms can damage roofs in different ways depending on wind speeds, hail size, falling debris, heavy precipitation, lightning, and other severe weather conditions. The type of damage matters when a roof claim is evaluated because an insurance assessment generally considers both the physical damage observed and the specific cause of the loss. However, identifying storm-related signs does not automatically establish coverage. Actual insurance coverage depends on the governing policy terms, exclusions, endorsements, and the unique circumstances of each claim. While educational calculators can help model financial outcomes once appropriate inputs are provided, they cannot inspect a roof or determine coverage.
Storm Damage Can Affect More Than the Shingles
A severe weather event rarely impacts only the topmost layer of a roof. Depending on the nature of the storm, damage can involve multiple integrated components of the roofing system, including underlayment, flashing, roof vents, ridge caps, valleys, gutters, downspouts, roof edges, and decking in certain circumstances.
Because a roof operates as a comprehensive system, evaluating the full structure helps provide a complete picture of the physical condition following severe weather, rather than focusing solely on the visible roof covering.
The Cause of Damage Matters
Roofs can experience various forms of physical distress from wind, hail, falling objects, water intrusion, or other storm events. Identifying the likely cause helps separate recent storm-related damage from pre-existing deterioration, long-term aging, or maintenance-related issues.
Distinguishing between these conditions is an important part of the evaluation process, though the final determination of whether a loss falls within the scope of policy provisions rests entirely on the insurance contract.
Common Types of Storm Damage to a Roof
Wind Damage
Strong winds can lift, loosen, crease, tear, or displace roofing materials and affect flashing and perimeter components.
Hail Damage
Hail can impact roofing materials, potentially leaving dents, fractures, bruising, or granule loss depending on severity.
Fallen Trees & Branches
Falling trees or branches can puncture, crush, crack, or displace roof components and structural elements.
Heavy Rain & Water Intrusion
Heavy rainfall can contribute to water entering through damaged roof areas, failed flashing, or other compromised pathways.
Tornado Damage
Tornadoes can create severe wind and debris impacts affecting both roof coverings and underlying building structures.
Hurricane & Tropical Storm
Hurricanes can expose roofs to extended high winds, wind-driven rain, flying debris, and prolonged storm conditions.
Lightning-Related Damage
Lightning can cause structural or electrical effects that may occasionally be associated with roof-related damage.
Debris & Impact Damage
Storm-driven debris or wind-borne objects can strike a roof and puncture or fracture roofing materials.
Storm Damage Is Not the Same as Normal Roof Wear
It is important to distinguish between damage associated with a specific severe weather event and normal wear that develops over time. Storm damage typically exhibits characteristics tied to a recent incident, such as fresh impact marks, recently displaced components, or localized tearing aligned with storm vectors. Normal wear, by contrast, involves gradual aging, weathering, environmental degradation, and long-term material breakdown.
A roof can sometimes display both storm-related damage and pre-existing wear simultaneously. Recognizing the difference helps clarify physical conditions, though policy language and claim review guidelines dictate how different conditions are handled.
Roof Components That May Need Evaluation After a Storm
Roof Covering
Shingles, tiles, metal panels, or other visible protective surface materials.
Ridge Caps
Specialized ridge elements susceptible to intense wind exposure and uplift forces.
Flashing
Metal seals around roof transitions, chimneys, and penetrations that may loosen.
Roof Vents
Exhaust and plumbing vents that can be damaged by wind or flying debris.
Gutters & Edges
Drainage components and perimeter edges affected by wind or heavy runoff.
Underlying Components
Underlayment and decking that may experience exposure if surface layers fail.
Storm Damage Type and What It Can Affect
| Storm or Event | Possible Roof Effects | What Still Needs to Be Determined |
|---|---|---|
| Wind | Lifted, displaced, torn, creased, or loosened materials | Extent of damage, cause, coverage, and applicable policy terms |
| Hail | Impact marks, fractures, bruising, or granule loss depending on material | Whether observed conditions are consistent with hail damage and covered under the policy |
| Falling Tree or Branch | Punctures, crushed areas, broken components | Extent of impact damage and applicable coverage |
| Heavy Rain | Water intrusion through damaged or vulnerable areas | Cause of entry, resulting damage, and policy coverage |
| Tornado | Severe wind and debris-related damage | Extent of covered damage and policy provisions |
| Hurricane / Tropical Storm | Wind, debris, and wind-driven rain effects | Applicable storm-related policy provisions and deductible |
| Lightning | Potential damage to roofing-adjacent or building components | Cause, extent, and applicable coverage |
| Debris Impact | Punctures, broken materials, or displaced components | Extent of impact and covered cause of loss |
Visible Roof Damage vs. Damage That May Not Be Obvious
Visible Damage
Examples include missing shingles, displaced roofing materials, broken tiles, obvious punctures, damaged flashing, and visible impact marks that can often be observed during an initial check.
Less Obvious Conditions
Some problems may not be immediately apparent without a closer look, such as compromised underlayment, water intrusion pathways, subtle flashing displacement, or moisture accumulation beneath surface layers.
Proper inspection may be needed to determine the actual condition of the entire roofing system.
Why the Same Storm Can Produce Different Roof Damage
Two roofs located in the exact same neighborhood can experience entirely different physical outcomes during the same severe weather event. Damage severity and type can vary significantly based on wind intensity, hail size, storm direction, roof pitch and orientation, roofing material type, roof age, existing maintenance condition, nearby trees, and previous repairs.
Because local site variables and micro-weather patterns influence how a storm interacts with a structure, generalized assumptions cannot accurately predict the specific physical impact on any individual property.
Factors That Help Describe Storm Roof Damage
Location of Damage
The specific roof slopes or areas affected can influence how conditions are reviewed.
Roof Material Type
Different materials show storm impact in distinct visual and physical ways.
Direction of Exposure
Wind and weather vectors affect roof faces differently based on exposure.
Severity of Event
Stronger storm forces create varying levels of physical stress on structures.
Existing Condition
Pre-existing wear or prior repairs provide context for current observations.
Extent of Damage
The scale of affected components helps outline the overall physical scope.
A Storm Event Does Not Automatically Establish Insurance Coverage
Identifying storm-related damage is only one part of an insurance claim evaluation. The governing policy may consider covered causes of loss, exclusions, endorsements, deductibles, policy limits, specific damage circumstances, pre-existing conditions, and required documentation.
This educational overview helps homeowners understand different types of roof damage and their general characteristics, but it cannot determine whether a particular loss is covered under any specific insurance policy.
What to Look For After a Storm
- Missing or displaced roofing materials
- Broken or cracked roof materials
- Visible impact marks
- Damaged flashing
- Damaged vents or roof penetrations
- Damaged gutters or roof edges
- Fallen branches or debris
- Signs of water intrusion
- Loose or exposed roofing components
- Changes not present before the storm
Do not climb onto a damaged or potentially unstable roof to inspect it yourself. A ground-level visual check can identify obvious conditions, but a qualified professional may be needed for a closer inspection.
Important About Storm Damage and Insurance Claims
Identifying a storm-related condition does not by itself determine coverage or the amount of an insurance payment. Claim evaluations depend on the cause of loss, actual damage scope, existing roof condition, policy terms, deductibles, settlement methods, and applicable endorsements. Calculators can help estimate financial scenarios once assumptions are entered, but they cannot diagnose damage or determine insurance coverage.
Key Takeaway
Storms can damage roofs through wind, hail, debris, falling objects, heavy rain, and other severe weather events, affecting both visible surface materials and underlying components. Because the same storm can produce different outcomes on different roofs, storm-related damage must be carefully distinguished from normal wear. Identifying the damage type is only one part of an insurance claim evaluation, as actual coverage depends on the applicable policy and claim circumstances. Educational calculators can assist with estimating financial scenarios, but they cannot diagnose damage or establish insurance coverage.
How Roof Damage Affects the Insurance Claim Estimate
An insurance claim estimate is directly influenced by the physical scope of work needed to address covered storm damage. The estimated scope depends heavily on where damage occurred, how extensive the impact is, which roofing components are affected, whether repair or complete replacement is appropriate, and the specific material and labor requirements involved. While physical damage assessment outlines the scope of work, it remains completely separate from the insurance policy's coverage definitions, valuation provisions, and settlement rules.
Limited Repair Scope
A smaller, localized area of damage often results in a more limited repair scope when the overall roof condition, material compatibility, and applicable policy circumstances support targeted repairs.
Examples may include repairing a small section of displaced materials, addressing specific damaged components, or replacing individual items where appropriate. The actual repair scope depends strictly on observed physical conditions and professional evaluation.
Larger Replacement Scope
More extensive damage can require a broader repair or replacement scope when supported by the overall roof condition, the extent of affected areas, and applicable property circumstances.
Examples may include widespread storm impact across multiple roof slopes or multiple damaged components requiring comprehensive work. Extensive damage does not automatically dictate full replacement without a proper physical evaluation and policy review.
Roof Damage Factors That Can Change the Estimate
Damage Location
The specific roof slopes or areas affected can influence which components and work areas are included.
Damage Extent
A larger affected physical area typically requires increased quantities of materials and labor.
Roofing Material
Shingles, tile, metal, and membrane systems have distinct installation and material specifications.
Roof Components
Flashing, vents, ridge caps, and valleys can be part of the affected scope when damaged.
Roof Accessibility
The pitch, height, and complexity of accessing work areas can influence labor assumptions.
Related Work
Tear-off, disposal, underlayment, and flashing replacement affect the total estimated scope.
The Damage Scope Is Different From the Insurance Valuation
Evaluating a storm-damaged roof involves two completely separate questions: first, determining what physical work is needed based on the roof's condition and repair or replacement scope; and second, determining how the insurance policy values, covers, and handles that work.
The valuation side involves coverage terms, settlement methods like RCV or ACV, depreciation, deductibles, policy limits, exclusions, and endorsements. Consequently, a larger physical repair scope does not automatically mean an insurer will pay the entire estimated amount, as policy provisions dictate final claim settlement rules.
How Roof Damage Can Become an Insurance Estimate
Identify the Affected Areas
Damaged roof areas and specific components are physically identified and documented.
Define the Work Needed
The repair or replacement scope is developed based on observed physical conditions.
Estimate Materials & Labor
The defined scope is translated into estimated quantities, materials, and labor requirements.
Apply the Claim Terms
The resulting estimate is considered alongside the policy deductible, valuation rules, and limits.
Example: Why the Same Storm Can Produce Different Claim Scopes
Roof A: Localized Damage
Damage is restricted to a single minor area or a small number of isolated roofing components following a minor storm vector.
Roof B: Multiple Affected Areas
Several distinct sections or components across different roof slopes require attention due to varied directional wind or hail exposure.
Roof C: Extensive Damage
A broad portion of the overall roofing system shows significant impact across multiple slopes, requiring comprehensive work.
The same severe weather event can produce vastly different physical outcomes and repair scopes depending on local variables. These conceptual examples do not determine insurance coverage or final claim amounts.
What Roof Damage Scope Can Change
| Damage or Scope Factor | Smaller Scope Example | Larger Scope Example | Potential Estimate Effect |
|---|---|---|---|
| Affected Area | One limited area | Multiple or broader areas | May change material and labor requirements |
| Roof Components | One component | Several components | May expand the work scope |
| Roofing Material | Limited material replacement | Larger material replacement | May change material and installation assumptions |
| Tear-Off | Limited or localized | More extensive | May affect labor and disposal assumptions |
| Underlayment/Flashing | Limited work | More extensive work | May increase the scope where required |
| Access/Complexity | Straightforward work area | More complex access or configuration | May affect labor assumptions |
These are conceptual examples only. They do not assign dollar amounts or imply that a larger scope guarantees full replacement coverage.
Roof Components That Can Influence the Scope
Shingles or Roof Covering
Damaged surface materials form a primary part of the physical repair or replacement scope.
Flashing
Compromised flashing transitions require targeted repair or replacement where appropriate.
Underlayment
Protective underlayment layers become part of the work scope when surface materials fail.
Ridge Caps & Valleys
These critical architectural intersections require specialized attention depending on damage.
Vents & Penetrations
Roof penetrations and exhaust vents can be affected and added to the scope when impacted.
Gutters & Roof Edges
Storm impact can sometimes damage drainage components or perimeter edges.
Repair vs. Replacement Is a Scope Question — Not Just a Cost Question
Determining whether a storm-damaged roof requires a localized repair or a broader replacement involves analyzing several technical variables, including the physical extent of damage, the condition of surrounding materials, repair feasibility, material compatibility, applicable building codes, and policy provisions.
Universal rules do not govern when a roof must be completely replaced. Instead, an accurate insurance estimate should reflect the documented physical scope rather than assuming that every storm-affected roof requires total replacement.
What Can Make a Roof Estimate More Detailed?
Multiple Roof Sections
Different roof slopes or sections often require separate scope descriptions.
Multiple Roofing Materials
Different material systems involve distinct work assumptions and costs.
Several Damaged Components
Flashing, vents, and edges add specialized items to the total scope.
Additional Work Requirements
Tear-off, disposal, and underlayment increase overall project requirements.
Complex Roof Geometry
Valleys, dormers, and steep pitches influence labor and safety variables.
Why a Roof Estimate Should Match the Actual Damage Scope
An estimate becomes significantly more meaningful when its listed work items correspond precisely to the roof areas and components actually evaluated.
A useful estimate makes it easy to understand what specific areas are included, what work is proposed, what materials are specified, which components are accounted for, and what underlying assumptions influence the overall scope. Transparency in documentation helps clarify how physical conditions translate into estimated figures.
Questions to Ask When Reviewing a Roof Damage Scope
- Which roof areas are included?
- Which roofing materials are included?
- Which damaged components are listed?
- Is the scope for repair or replacement?
- Are tear-off and disposal included where applicable?
- Is underlayment included where appropriate?
- Are flashing and roof penetrations addressed?
- Are gutters or roof-edge components included if affected?
- Does the scope describe the actual damage being evaluated?
- Are there assumptions that could materially change the estimate?
This checklist helps organize the scope. It does not determine insurance coverage or the final settlement.
Important About Roof Damage Estimates
A roof damage estimate is an assessment of the work and cost associated with a defined scope. The final insurance treatment depends on coverage rules, RCV or ACV settlement methods, depreciation, deductibles, policy limits, exclusions, endorsements, and claim-specific requirements. Calculators can demonstrate how different damage and scope assumptions affect an estimate, but they cannot inspect a roof or determine an insurer's final scope.
Key Takeaway
The physical scope of roof damage serves as a foundational input to an insurance claim estimate. Location, extent, materials, components, labor, and related work all change the estimated scope, meaning a localized repair produces very different figures than a broader replacement scope. Because the physical damage scope remains completely separate from insurance valuation rules, final claim amounts ultimately depend on documented work scopes and applicable policy terms. Educational calculators can assist with modeling financial scenarios, but they cannot inspect property damage or establish insurance coverage.
Ready to Estimate Your Storm Damage Payout?
Use the Storm Damage Roof Insurance Claim Calculator to quickly project your expected insurance payout, subtract your deductible, and view out-of-pocket costs.
Calculate Your Insurance ClaimWhat Information Do You Need for a Storm Damage Roof Claim?
Having organized property, roof, storm, damage, insurance, and estimate information can make it significantly easier to describe the loss and evaluate an insurance claim estimate. The exact information needed can vary depending on your property, roof specifics, the storm event, your insurance policy terms, the nature of the damage, and overall claim circumstances. The calculator uses user-provided assumptions and information to produce an estimate, while actual claim handling depends strictly on the applicable insurance policy and professional claim evaluation.
Property and Roof Information
Basic property and roof details help establish what specific type of roof and structure are being evaluated. Having these baseline characteristics ready ensures consistency when developing or reviewing an estimate.
- Property location and address
- Approximate roof age or installation history
- Primary roofing material type
- Total roof size or approximate square footage
- Number of distinct roof sections or slopes
- Roof configuration, pitch, or complexity
Insurance and Policy Information
Policy-related information can affect how an estimate is interpreted under your specific coverage terms. While policies vary widely, having this contextual paperwork ready can provide necessary clarity.
- Insurance carrier name and contact details
- Policy or declarations page overview
- Applicable deductible amount or percentage
- Settlement or valuation method (e.g., RCV vs. ACV)
- Applicable policy terms or endorsements
- Special storm-related deductible information when applicable
Key Information Categories
Property Address or Location
The property location identifies the home and may also be relevant to the regional storm event and policy context.
Roof Age
Approximate installation age can matter when considering roof condition, depreciation, and valuation assumptions.
Roofing Material
Asphalt shingles, metal, tile, or other systems can directly affect repair or replacement estimation assumptions.
Roof Size & Configuration
Total surface area and structural complexity can influence the overall scope of work being estimated.
Insurance Policy
Policy declarations help identify applicable coverage terms, limits, and general valuation provisions.
Deductible & Settlement Terms
Deductibles and valuation approaches (like ACV or RCV) can affect how an estimate is interpreted.
Information About the Storm Event
Useful storm-event information may include the date of the storm, approximate time, type of storm, wind, hail, tornado, hurricane, or other event descriptions when applicable, available weather information or records, and when the damage was first noticed.
The storm date and cause of damage should not be guessed when reliable information is available. This section is informational only; it does not invent weather data or claim a specific storm caused damage unless supported by evidence.
Damage Information to Have Ready
Damage Information
A basic descriptive summary of what appears physically damaged across the property.
Roof Areas Affected
Slopes, ridges, valleys, edges, roof penetrations, or other specific locations showing impact.
Visible Conditions
Missing materials, lifted or displaced roofing, impact marks, damaged flashing, or debris effects.
Related Interior Damage
Water intrusion or other related conditions inside the property that may be relevant to the loss.
Previous Roof Work
Information regarding prior repairs, replacements, or general maintenance history.
Contractor or Inspection Details
Professional inspection reports or roofing estimates providing findings on observed damage.
What Information May Be Useful for a Storm Damage Roof Claim?
| Information Category | Examples | Why It May Matter |
|---|---|---|
| Property | Address or location | Identifies the property being evaluated |
| Roof | Age, material, size, configuration | Helps describe the roof and estimate scope |
| Storm | Date, event type, approximate timing | Helps establish the reported storm event |
| Damage | Affected areas, visible conditions, related damage | Helps describe the physical loss being evaluated |
| Policy | Deductible, valuation method, policy terms | Helps interpret the estimate under the applicable policy |
| Estimate | Roofing estimate, inspection findings, scope of work | Helps connect observed damage with proposed work |
These examples are for informational reference only. No single item guarantees coverage, approval, or final claim payment.
Information You Know
Some information may be readily available from your personal records, making it simple to reference or input into an estimate. This can include immediate details such as your property address, basic visual observations, known incident dates, or general property notes.
Information That May Need Verification
Other details may require confirmation through official documents or professional assistance. Verifying installation dates, exact roof measurements, deductible rules, and settlement provisions ensures greater accuracy when evaluating estimated figures.
Do Not Guess Important Claim Details
Entering incorrect information can significantly alter an estimate. Inaccurate inputs such as an incorrect roof age, wrong roof size, mistaken roofing material, erroneous deductible amounts, or incorrect storm dates can misrepresent the expected scope.
When possible, users should verify important details using policy declarations pages, prior invoices, building permits, property records, professional inspection findings, or contractor estimates rather than relying on guesswork.
Useful Documents and Records
Insurance Policy / Declarations
Provides critical insight into coverage limits, deductibles, and settlement types.
Prior Roof Invoice / Permit
Helps establish accurate roof age and past construction material specifications.
Maintenance & Repair Records
Outlines the service history and maintenance background of the roofing system.
Photos or Video
Visual records that capture general physical conditions (detailed documentation is covered separately).
Roofing Estimate / Report
Professional inspection findings detailing observed damage and recommended scopes.
What the Calculator Can Use
The calculator can utilize distinct categories of user-provided information—including roof size, roof material, roof age, damage scope, estimated repair or replacement cost, deductible, depreciation assumptions, and settlement terms—to structure an estimate.
The calculator organizes these inputs into an estimate based strictly on the parameters entered. It does not inspect roofs, determine coverage, replace insurance policies, or substitute for an insurer's formal claim evaluation.
Before Entering Information Into an Estimate
- Confirm the approximate roof size
- Confirm the roofing material
- Check the roof age or installation history
- Identify the general damage scope
- Record the storm date if known
- Confirm the applicable deductible
- Check whether the policy uses ACV, RCV, or another valuation method
- Review available inspection or roofing estimate information
This checklist assists with organizing details. It does not establish insurance coverage or final settlement amounts.
Important About Roof Insurance Claim Information
Insurance policies, deductibles, valuation methods, claim procedures, and coverage provisions vary across carriers and regions. The information needed to run a helpful estimate may differ from the formal documentation ultimately requested by an insurer during a claim investigation. Always consult your specific policy documents.
Key Takeaway
A useful storm damage roof claim estimate starts with accurate information regarding the property, roof, storm event, damage conditions, insurance policy, deductible, valuation assumptions, and estimated repair or replacement scope. Verified details produce a significantly more meaningful estimate than guesses or incomplete assumptions, helping homeowners organize their approach before reviewing financial scenarios.
What to Document After Storm Damage to Your Roof
Documenting the condition of a property after a storm helps create a clear, factual record of what was observed, when it was observed, and what areas may have been affected. Useful documentation may include roof conditions, exterior damage, interior signs of water intrusion, fallen trees or debris, damaged property components, storm timing, temporary protective measures, and estimates or inspection records. Documentation should accurately reflect what was observed and should not include assumptions presented as facts, nor does it guarantee insurance coverage or claim approval.
Document the Condition Before Cleanup
When it is safe to do so, homeowners can create a chronological record of visible conditions before damaged materials are removed or the property is cleaned up. Capturing the state of the roof, siding, gutters, windows, exterior structures, fallen branches or trees, and visible debris helps preserve the immediate post-storm context.
Document Only What You Can Safely Observe
Roofs can be exceptionally dangerous after severe weather events. Do not climb onto a damaged, wet, or steep roof simply to take photographs. Do not walk through unstable areas or approach downed power lines. Use ground-level observations when appropriate, and rely on qualified professionals for areas that cannot be safely inspected.
Roof and Exterior Conditions to Record
Roofing Materials
Visible conditions may include missing, displaced, lifted, cracked, or broken materials (recorded conditionally).
Ridge Caps, Valleys & Edges
Critical architectural intersections can be worth noting if they can be safely observed from the ground.
Flashing & Penetrations
Visible conditions around vents, chimneys, skylights, and flashing assemblies.
Gutters & Downspouts
Dents, separation, displacement, blockage, or debris accumulation.
Siding, Windows & Exterior
Storm events can affect broader exterior zones; related conditions form part of the record.
Trees, Branches & Debris
Fallen trees, heavy branches, or storm-related structural debris near the property.
Record What You See — Not What You Assume
It is important to distinguish between observation, interpretation, and conclusion. For example, an observation notes that “a section of roofing material appears displaced,” whereas an interpretation might suggest “the displacement may be consistent with wind exposure,” and a conclusion might claim “the wind definitely caused the damage.”
Documentation should focus strictly on what can actually be observed and should avoid presenting uncertain causes as established facts. This distinction is especially vital when compiling information for property records and insurance evaluations.
Other Property Conditions to Document
Ceiling or Wall Stains
Visible water stains, discoloration, or finishing changes inside the property.
Attic or Interior Areas
Safely accessible attic spaces showing signs associated with water intrusion.
Windows & Doors
Visible storm-related conditions or operational shifts around openings.
Exterior Structures
Detached garages, sheds, fences, or outbuildings (coverage terms vary).
Personal Property
Visibly affected belongings or contents when applicable to the loss.
Active Leaks or Moisture
Active leaks or newly observed moisture documented promptly when safe.
What to Document and Why It May Matter
| Area | Examples of What to Record | Why It May Matter |
|---|---|---|
| Roof | Visible roofing conditions | Helps establish the observed roof condition |
| Exterior | Siding, gutters, windows, trim | Helps show whether other exterior areas were affected |
| Debris | Fallen branches, trees, displaced materials | Helps establish surrounding storm conditions |
| Interior | Stains, visible moisture, damaged finishes | Helps record possible related interior conditions |
| Timing | Storm date, when damage was noticed, when conditions changed | Helps create a chronological record |
| Temporary Protection | Emergency measures taken to limit additional damage | Helps record what was done after the event |
| Inspection | Contractor or professional observations | Provides an additional record of observed conditions and proposed work |
This table is for educational reference. Documentation creates a record of conditions; it does not automatically prove coverage.
Photos and Video Can Create a Useful Record
Photographs and video capture overall property conditions, affected areas, close-up details, and surrounding context. Taking enough wider context shots helps establish where specific close-up images were taken, eliminating confusion later on.
Keep the Original Files When Possible
Retaining original digital files preserves metadata such as timestamps and camera details. Keeping photos organized in clearly labeled folders or backups ensures that your post-storm record remains easy to review and reference.
A Simple Storm Damage Documentation Process
Check Safety First
Prioritize personal safety before attempting any observation or documentation.
Capture Overall Condition
Take wider context shots of the property, roof lines, and surrounding yard.
Record Specific Details
Take closer images of visible damage or affected components from safe positions.
Organize Information
Keep photos, notes, inspection notes, and receipts together chronologically.
Document Temporary Protective Measures
After a storm, a property owner may need to take reasonable, safe temporary steps to reduce the risk of additional damage, depending on the situation. Examples may include covering an opening when safely possible, removing loose debris from an accessible area, or contacting a qualified professional.
Records of temporary protective measures—such as receipts for tarps or notes on emergency work—help establish a clear timeline of post-storm activity. Insurance policies and procedures vary regarding temporary measures, so keeping organized documentation of actions taken is helpful.
Keep Related Records Together
Photos & Video
Visual files capturing conditions across the property over time.
Written Notes
Simple logs recording dates, times, observations, and weather notes.
Inspection Reports
Professional evaluations detailing observed physical conditions.
Roofing Estimates
Contractor proposals detailing recommended scope of work.
Repair Receipts
Invoices and receipts for emergency materials or temporary work.
Why Timing and Organization Matter
Storm damage conditions can change rapidly after an event due to subsequent weather, temporary repairs, ongoing cleanup, water migration, or professional work. Establishing an organized timeline makes it much easier to distinguish between what was observed initially, what occurred afterward, what temporary measures were taken, and what work was subsequently proposed or completed.
While timing records do not determine insurance coverage, they provide helpful historical context for property evaluations.
Storm Damage Documentation Checklist
- Record the storm date if known
- Record when damage was first noticed
- Photograph the property from safe locations
- Capture wider images for context
- Capture closer images of visible damage
- Document affected exterior areas
- Document visible interior conditions
- Record fallen trees, branches, or debris when relevant
- Keep notes about temporary protective measures
- Save inspection reports, estimates, receipts, and related records
This checklist is designed to help organize your documentation workflow.
Safety Comes Before Documentation
Do not climb onto a damaged, wet, unstable, or steep roof simply to obtain photographs. Do not approach downed electrical lines, unstable structures, dangerous debris, or visibly unsafe areas. Always rely on ground-level observations or qualified professionals when necessary. Your safety is far more important than any property documentation.
Documentation Does Not Determine Coverage
Photographs, notes, videos, inspection reports, and estimates help describe the physical condition of a property, but they do not by themselves determine whether a loss is covered under an insurance policy. Coverage and claim handling depend entirely on the applicable policy terms, factual circumstances, and professional claim evaluation.
Key Takeaway
Good storm damage documentation should be accurate, focus on observable conditions, be well-organized, preserve timing, include relevant property areas, and prioritize personal safety above all else. The primary goal is to create a clear, factual record of the property's condition following an event rather than assuming causes or coverage outcomes. Organized records provide valuable context for reviewing potential repair scopes and policy terms.
Ready to Estimate Your Storm Damage Payout?
Use the Storm Damage Roof Insurance Claim Calculator to quickly project your expected insurance payout, subtract your deductible, and view out-of-pocket costs.
Calculate Your Insurance ClaimHow to File a Storm Damage Roof Insurance Claim
Filing a roof insurance claim generally involves reviewing the applicable policy, documenting the damage, notifying the insurer, providing requested information, allowing the insurer or its representative to evaluate the loss, and reviewing the resulting estimate or claim information. Exact procedures and deadlines vary by insurer, policy, location, type of loss, and the specific circumstances of the claim. Understanding the general workflow can help homeowners navigate the reporting process smoothly.
Start With Your Policy and Available Information
Before contacting the insurer, homeowners may want to review available policy information and organize relevant details. This includes policy or declarations information, deductible amounts, valuation methods when known, roof details, the storm date, visible damage records, and available documentation.
Report the Loss to the Appropriate Insurer
The homeowner generally contacts the insurer or applicable claims channel to report the loss. During this initial contact, you may be asked for property information, policy details, the date of loss, a description of the damage, contact info, and other supporting specifics. The insurer will typically explain its next steps after the report is logged.
General Storm Damage Roof Claim Process
Review Policy Information
Identify relevant policy terms and understand basic provisions such as deductibles and valuation methods.
Document the Damage
Preserve an accurate, factual record of the observed property conditions following the storm event.
Report the Loss
Contact the insurer or designated claims channel to officially open the claim and provide initial details.
Provide Supporting Info
Submit requested photographs, estimates, inspection notes, or receipts when requested by the insurer.
Allow Property Evaluation
Accommodate any property inspections or evaluations arranged by the insurer to review reported damage.
Review Claim Information
Examine the resulting estimate, scope, deductible, and valuation details provided by the insurance carrier.
Report the Loss Using the Insurer’s Current Claims Process
Insurers may offer different ways to report a claim, such as phone support, online claims portals, mobile applications, or through a local agent. Homeowners should use the current method provided by their specific insurance company or policy documentation.
Information You May Be Asked to Provide
Property Information
Property address, contact info, and occupancy details when relevant to the loss.
Policy Information
Policy number, insurer identity, and declarations overview.
Date of Loss
When the storm or damage occurred or when it was first noticed.
Damage Description
A description of what was observed and which areas appear affected.
Supporting Records
Photographs, videos, inspection reports, estimates, or receipts.
Emergency Measures
Details regarding temporary steps taken after the storm to limit damage.
What to Say When Reporting the Damage
A useful initial description should focus on observable facts: what happened, when it happened or was noticed, what areas appear affected, whether there is visible interior damage, and whether temporary protection was needed. Factual descriptions are much more helpful than unsupported conclusions.
What Not to Assume
Homeowners should avoid assuming that every visible condition was caused by the storm, that every damaged item is automatically covered, that the insurer will use a contractor's exact estimate, or that full roof replacement is guaranteed. Keep expectations aligned with policy terms.
Keep Your Claim Information Organized
Keeping claim-related information together can make the process significantly easier to manage. Maintain an organized folder containing claim correspondence, inspection records, estimates, photos, receipts, policy documents, and brief notes about phone calls or conversations.
What Happens at Each General Stage?
| Stage | What You May Provide | What May Happen Next |
|---|---|---|
| Policy Review | Policy and property information | You identify relevant claim information and questions |
| Damage Documentation | Photos, notes, visible conditions | A clearer record of the reported loss is created |
| Claim Report | Date of loss and damage description | The insurer opens or records the claim according to its process |
| Supporting Information | Estimates, reports, photos, receipts | The insurer may request or review additional information |
| Property Evaluation | Access or inspection information when applicable | The reported damage may be evaluated |
| Claim Review | Estimate, scope, valuation, deductible info | Claim information or settlement details may be provided for review |
Stages and procedures vary by insurer, policy terms, and individual claim circumstances.
Keep the Damage Scope Separate From the Coverage Question
Filing a claim involves two distinct questions: First, what physical damage exists and what work may be needed? Second, what part of that loss is covered under the applicable policy? Documenting and estimating the physical damage does not by itself determine coverage terms.
Before You Report the Claim
Review Policy
Review available policy information and deductible details.
Record Date
Note the storm date or when damage was first observed.
Document Conditions
Capture safe visual records of the property condition.
Gather Records
Collect inspection reports, estimates, and receipts.
Factual Description
Prepare a clear description of the observed damage.
Questions You May Want to Ask the Insurer
- What is my official claim number?
- What specific information or documentation do you need from me?
- What is the applicable deductible amount for this claim?
- What valuation method applies to the roof under my policy?
- How will the property inspection be scheduled and handled?
- What is the expected next step after the initial claim report?
Claim Procedures Vary
Claim reporting methods, inspections, documentation requests, timelines, and settlement procedures differ across insurance companies, policies, geographic locations, and types of loss. The applicable policy and the insurer's current claims process govern the specific handling of any claim.
Key Takeaway
Filing a storm damage roof insurance claim generally starts with understanding available policy information, documenting the observed damage, reporting the loss, providing requested information, participating in the evaluation process, and reviewing the resulting claim information. The exact process varies by insurer, and accurate, factual information is always more useful than assumptions.
Should You File a Roof Insurance Claim or Pay for Repairs Yourself?
When a roof is damaged by a storm, homeowners frequently consider different ways to handle the repair cost. Deciding whether to pursue an insurance claim under an applicable policy or pay for some or all repairs directly involves evaluating more than just the immediate repair estimate. Key factors can include the estimated repair or replacement cost, applicable deductibles, roof age, depreciation, settlement valuation methods, policy terms, damage scope, available funds, previous claims considerations, and whether the loss appears potentially covered. Understanding these variables can help homeowners review their own circumstances without relying on rigid assumptions.
Considering an Insurance Claim
Pursuing an insurance claim under a policy typically involves reporting the loss, navigating deductible provisions, coordinating inspection or claim evaluation, determining coverage applicability, and reviewing repair or replacement estimates. Homeowners may also consider factors such as actual cash value (ACV) versus replacement cost value (RCV), possible depreciation, and insurer-specific claim procedures. This path focuses on utilizing the applicable policy terms to address the reported damage.
Considering Direct Payment
Paying for repairs directly involves obtaining a contractor estimate, funding the project out of pocket using personal savings or other resources, and addressing the repair work without opening an insurance claim. Opting for direct payment does not automatically mean insurance coverage is unavailable; rather, it represents a conscious choice to handle the financial responsibility directly. This path avoids the formal claim process and focuses solely on direct contractor arrangements.
Factors That May Affect the Decision
Estimated Repair Cost
The expected cost of the work provides a baseline number to compare with the applicable deductible and other potential expenses.
Insurance Deductible
The deductible represents the specific portion of a covered loss that the policyholder may be responsible for under the policy terms.
Roof Age and Condition
Roof age and existing wear can influence depreciation, valuation methods, repair scope, and overall estimate interpretations.
Settlement Method
Whether a policy uses ACV, RCV, or another valuation structure can alter how an insurance payout is calculated and understood.
Damage Scope
A localized repair project and a full roof replacement involve drastically different financial figures and comparison dynamics.
Policy Terms
Specific exclusions, conditions, endorsements, and deductible clauses within the policy language shape the claim framework.
Compare the Potential Claim Amount With the Actual Repair Cost
Conceptually, a homeowner may look at the relationship between the estimated covered repair or replacement amount, the applicable deductible, any depreciation or non-recoverable items when relevant, and the total roofing estimate. Calculators and estimators can help organize these inputs and assumptions, but the actual claim outcome ultimately depends on the specific policy terms and the insurer's evaluation process.
Questions About the Insurance Option
Homeowners evaluating the insurance path may want to consider questions such as: What specific damage appears potentially covered? What deductible applies under the policy? Is the roof evaluated using ACV, RCV, or another method? Is depreciation involved in the calculation? What documentation is required by the carrier? What formal claim procedures apply?
Questions About Paying Directly
Homeowners evaluating direct payment may want to consider questions such as: What is the actual contractor repair estimate? Is the necessary work confined to a small area or broader? What personal funds or financing options are available? Is immediate repair required to prevent further exposure? What work is essential versus optional? What warranty or contractor terms apply?
A Small Repair and a Full Roof Replacement Are Different Comparisons
The decision factors involved in evaluating a claim versus direct payment can change significantly depending on the physical scope of the storm damage.
Scenario 1: Localized Repair
A limited area of the roof requires attention, which may involve lower total project costs that interact differently with standard deductibles.
Scenario 2: Multiple Damaged Areas
Several distinct sections or components across the roof surface require repairs, expanding the overall project scale and financial scope.
Scenario 3: Larger Replacement Scope
A broader roofing project or full replacement is under consideration, bringing comprehensive valuation methods, RCV/ACV rules, and larger figures into play.
Insurance Claim vs. Direct Payment: What to Compare
| Factor | Insurance Claim Consideration | Direct Payment Consideration |
|---|---|---|
| Repair Cost | Compare the estimated covered loss with the total repair estimate | Compare the full repair estimate directly with available funds |
| Deductible | An applicable deductible may reduce the total claim payout | There is no insurance deductible if no claim is pursued, but the homeowner pays the contractor directly |
| Roof Age | May affect depreciation calculations and valuation terms | May still influence repair scope and contractor estimates |
| Settlement Method | ACV, RCV, or another policy method may govern the financial adjustment | Focuses entirely on actual contractor pricing and payment terms |
| Damage Scope | Coverage and valuation depend on the formally evaluated scope | Involves evaluating the cost of the specific repair work being performed |
| Policy Terms | Policy language, endorsements, and conditions directly shape the process | Policy terms are less directly relevant when paying entirely out of pocket |
Other Factors to Consider
Available Funds
Paying directly requires having sufficient liquid savings or other viable payment arrangements in place.
Urgency of the Repair
Active leaks, exposed decking, or worsening weather exposure can create a need to address physical problems promptly.
Previous Roof Work
Prior repairs, past replacements, or maintenance history can impact current estimates and roof condition records.
Other Policy Considerations
The policy may contain specific provisions, deadlines, or conditions relevant to reporting property damage.
Claims History
Homeowners may want to understand how their insurer and policy handle prior claims or overall claims tracking.
Future Repair Needs
Evaluating whether current work resolves the identified problem or if unrelated roof maintenance will still be required.
Do Not Base the Comparison on One Number Alone
Evaluating a roof insurance decision involves looking at a combination of variables rather than simply matching a repair cost against a deductible. Factors such as total estimates, depreciation, settlement methods, potentially covered scope, non-covered work, and available funds all interact. Calculators and worksheets help organize these inputs to provide clarity, but they do not make the final decision for the homeowner.
Verify These Details Before Comparing the Options
Roof Repair Estimate
Confirm the current contractor estimate and detailed scope of work.
Applicable Deductible
Confirm the exact deductible amount listed under the relevant policy.
Roof Age
Verify approximate installation dates or historical maintenance records.
Valuation Method
Check if the policy utilizes ACV, RCV, or another specific valuation structure.
Damage Scope
Ensure any cost comparison evaluates the exact same physical scope of work.
Questions to Work Through Before Deciding
- What is the estimated total repair or replacement cost?
- What deductible applies under the current insurance policy?
- What valuation method does the policy use for the roof?
- How old is the roof system?
- What specific damage appears directly related to the storm event?
- What work is included in the roofing contractor's estimate?
- What portion of the estimate may fall outside the insurance scope?
- What would paying directly require in terms of available funds and financial timing?
Insurance and Repair Decisions Are Situation-Specific
There is no single formula or universal calculation that dictates whether a homeowner should file an insurance claim or pay out of pocket. Relevant factors vary widely depending on policy language, deductibles, roof condition, damage scope, valuation methods, insurer procedures, repair costs, and individual financial circumstances.
Key Takeaway
Comparing an insurance claim with paying directly involves looking at the complete picture rather than focusing on a single number. By evaluating repair costs, deductibles, roof age, damage scope, valuation methods, policy terms, available funds, and claim considerations, homeowners can organize their options and ask informed questions. This evaluation framework supports objective analysis without dictating which path to choose.
Why Your Insurance Claim Estimate May Differ From Your Roofing Estimate
When a storm damages a roof, homeowners frequently receive multiple estimates from different sources, such as an insurance claim estimate and a roofing contractor's proposal. These documents may not always match in their final totals, line items, or scope of work. Differences do not automatically mean one estimate is incorrect. Variations can arise from different measurements, damage scopes, material assumptions, labor requirements, pricing databases, line item structures, valuation methods, or the specific purpose for which each estimate was prepared. Understanding these legitimate differences can help homeowners compare the figures objectively without relying on assumptions.
Insurance Claim Estimate
An insurance estimate is generally structured around the insurer's evaluation of the reported loss under the terms of the applicable policy. It may account for the covered damage being evaluated, calculated quantities, labor assumptions, material specifications, applicable pricing, potential depreciation, deductible information, and other claim-specific guidelines. This document reflects how the insurer calculates the claim value based on policy provisions.
Roofing Contractor Estimate
A roofing contractor estimate generally focuses on the physical work the contractor proposes to perform and the expected cost of executing that work. It may detail removal, materials, installation labor, specific roof components, required accessories, site-specific work, and business overhead. Contractor estimates can also differ from one another based on business models, local rates, and proposed material grades.
Common Reasons Two Estimates May Differ
Different Measurements
Roof measurements, pitch calculations, or total surface areas evaluated may vary between estimators.
Different Damage Scope
One estimate may include more, fewer, or differently categorized affected areas than the other.
Different Materials
Estimates may specify different material grades, manufacturer lines, or replacement components.
Different Labor Assumptions
Labor requirements and rates can vary based on roof accessibility, steepness, and proposed techniques.
Different Line Items
One estimate may include specific accessories or steps that another estimate does not list separately.
Different Pricing
Estimates can draw from different pricing databases, regional cost scales, or contractor-specific overhead.
Scope Differences Can Matter More Than the Total Price
Before comparing final totals, homeowners can benefit from comparing what work is actually included in each document. One estimate might list comprehensive items such as removal, disposal, underlayment, flashing, vents, ridge caps, drip edge, starter materials, and installation, while another may group or omit certain details depending on the proposed scope.
Two totals cannot be meaningfully compared if the underlying work or material specifications are different. Always review the underlying scope to see what items are included, optional, or excluded when applicable.
Roofing Items Worth Comparing
Roof Covering
Compare the material specification, quantity, replacement area, and waste assumptions when shown.
Underlayment
Compare whether protective underlayment is included and what type or weight is specified.
Flashing
Compare flashing details around chimneys, walls, valleys, and other relevant roof junctions.
Ridge Caps & Starter
Compare whether specialized ridge cap shingles and starter strip materials are accounted for.
Vents & Penetrations
Compare roof vents, plumbing boots, pipe flashing, and related roof penetration components.
Removal & Disposal
Compare tear-off labor assumptions, hauling fees, and debris disposal provisions.
When the Insurance Estimate Is Lower
A lower insurance estimate can reflect differences in measured scope, pricing databases, included accessories, material tier assumptions, or policy valuation rules. It does not automatically mean an error occurred; rather, it indicates a difference in how the insurer evaluated the claim variables compared to the contractor's proposal. Identifying the exact differences is a useful first step.
When the Roofing Estimate Is Higher
A higher contractor estimate can reflect a broader proposed scope, premium material upgrades, additional structural or ventilation components, detailed labor assumptions, local market pricing, or work the contractor believes is necessary to complete the project properly. This reflects the contractor's professional pricing for the requested work.
Compare the Estimates Line by Line
| Category | Insurance Estimate | Roofing Estimate | What to Compare |
|---|---|---|---|
| Roof Area | Listed or calculated roof surface area | Contractor's measured or estimated area | Check whether the same physical surface area is being priced |
| Materials | Material and specification details | Material and specification details | Compare material type, grade, quality tier, and system compatibility |
| Labor | Listed labor line items and rates | Contractor labor scope and pricing | Compare what installation and handling work is included |
| Roof Components | Flashing, vents, underlayment when listed | Contractor's proposed components | Check whether the same accessories and protective components are included |
| Removal | Tear-off and removal assumptions | Contractor removal scope | Compare quantities of layers removed and disposal provisions |
| Pricing | Estimate unit prices and totals | Contractor unit prices and totals | Compare pricing structure, unit costs, and overall calculations |
| Depreciation | May be shown when applicable to the policy | Usually not presented as a depreciation deduction | Understand whether the comparison involves gross cost or adjusted claim value |
| Deductible | Shown as part of the claim calculation | Usually not a contractor pricing line item | Keep the policy deductible separate from the physical repair cost |
Compare Scope Before Comparing Dollars
Comparing an insurance estimate total directly against a contractor estimate total without checking the underlying components does not explain why the numbers differ. Homeowners can gain clarity by reviewing roof area, damage scope, materials, quantities, labor, components, removal, disposal, and other listed work first, and interpreting the financial totals only after the scope is fully understood.
Questions to Ask When Estimates Differ
Are Measurements Aligned?
Do both estimators use the same roof dimensions and pitch calculations?
Is the Damage Scope Identical?
Does each document account for the exact same physical damaged areas?
Are Materials Comparable?
Do the estimates specify matching material grades and system types?
Are Components Included?
Are flashing, vents, underlayment, and disposal included in both?
Do Pricing Bases Vary?
How do pricing databases or contractor rate assumptions differ?
An Insurance Estimate and a Contractor Estimate May Serve Different Purposes
An insurance estimate is generally prepared to evaluate a reported loss and calculate claim figures under policy provisions. A contractor estimate is generally prepared to propose a complete project scope and price for performing physical work. Because these documents serve different administrative and operational functions, differences in formatting, line item organization, and totals are common.
What to Check in the Insurance Estimate
Review the insurance document for roof area measurements, evaluated damage scope, material descriptions, quantity calculations, labor line items, applicable depreciation, deductible references, and any items noted as included or excluded under the policy framework.
What to Check in the Roofing Estimate
Review the contractor document for roof measurements, proposed work descriptions, material grades, quantities, labor terms, removal and disposal provisions, accessory components, and total project pricing figures.
Different Estimates Do Not Automatically Mean a Disagreement
Variations between an insurance estimate and a contractor estimate frequently stem from differing measurements, scopes, assumptions, pricing models, and underlying purposes. Identifying the exact source of any discrepancy is far more informative than focusing solely on the final monetary difference.
Insurance Claim Value Is Not the Same as Contractor Price
A contractor's proposed project price and an insurance claim calculation represent different concepts. A contractor estimate outlines the complete cost of performing work. An insurance claim calculation additionally incorporates policy-related valuation rules, deductibles, depreciation, and covered versus non-covered scope boundaries. Comparing them requires looking beyond raw numbers.
Key Takeaway
Insurance and roofing estimates can differ for legitimate reasons, including measurements, damage scope, materials, labor, line items, pricing, depreciation, deductibles, and policy-related assumptions. The most effective way to evaluate these figures is to conduct a line-by-line comparison of the scope and underlying assumptions rather than simply comparing final totals. This balanced approach provides clarity without assuming either estimate is inherently wrong.
Ready to Estimate Your Storm Damage Payout?
Use the Storm Damage Roof Insurance Claim Calculator to quickly project your expected insurance payout, subtract your deductible, and view out-of-pocket costs.
Calculate Your Insurance ClaimWhat Happens After a Storm Damage Roof Insurance Claim Is Filed?
After a storm damage roof insurance claim is reported, the insurer generally initiates a structured evaluation process. This process can involve recording the claim, reviewing submitted details and policy provisions, requesting additional documentation when necessary, arranging or conducting an inspection or physical evaluation, and developing a damage scope and estimate. The insurer then communicates information regarding policy coverage, valuation, or next steps. Because every claim involves unique circumstances, policy terms, and property conditions, the exact sequence and timing can vary considerably. Understanding the general post-filing framework helps homeowners follow each stage smoothly without anticipating a single universal outcome or timeline.
The Claim Is Reviewed
Following submission, the insurer typically reviews the details provided with the claim, including policy information, the reported storm event, descriptions of property damage, photographs, estimates, and other supporting records. During this phase, the insurer may identify information that is missing, incomplete, or requires clarification before proceeding further.
The Property May Be Inspected or Further Evaluated
To better understand the reported condition and physical loss, the insurer may arrange an inspection or another evaluation method. This can involve examining the roof surface, exterior components, interior spaces, or other relevant property areas depending on the nature of the reported storm damage and the specific claim circumstances.
The General Post-Filing Claim Process
Claim Is Assigned or Recorded
The insurer records the reported loss and provides claim-related reference details, such as a claim number or contact information for tracking purposes.
Initial Information Is Reviewed
Submitted records, policy details, and property descriptions are reviewed to understand the reported event and supporting context.
Property Is Inspected or Evaluated
An inspection or evaluation may be conducted to document observable physical conditions and examine reported damage areas.
Damage Scope and Estimate Are Developed
Observed damage may be organized into a repair or replacement scope and associated estimate depending on the claim circumstances.
Coverage and Valuation Information Is Communicated
The insurer communicates details regarding how the reported loss is evaluated under policy provisions, including applicable claim amounts.
Next Steps Are Identified
The claim moves toward documentation follow-ups, payment processing, or repair planning based on the ongoing claim evaluation.
The Inspection Is About the Observed Condition
An inspection can help document the physical condition of the roof, visible storm-related effects, affected roof areas, damaged components, related exterior or interior conditions, and the apparent scope of work. It is important to note that observing physical damage and determining whether that damage is covered under a particular policy are separate questions handled through policy administration.
Information the Insurer May Request
Photos and Video
Photographs or video may help document visible property conditions before or after filing.
Roofing Estimate
An estimate from a roofing professional may be requested or provided as supporting information.
Inspection Report
An inspection report may provide additional details regarding observed roof or property conditions.
Receipts and Invoices
Receipts or invoices may document temporary repairs, materials, or related expenses when relevant.
Policy & Property Details
The insurer may need specific policy, property, or loss information to process the claim accurately.
Additional Damage Info
Further details may be requested if initial records do not fully describe the reported loss.
The Claim Estimate May Change
The estimate or damage scope may change when additional information becomes available, measurements are clarified, previously unobserved damage is documented, or other relevant factors are considered. Adjustments are part of the evaluative process and do not imply a static or unalterable calculation.
The Claim Information May Contain Several Separate Amounts
Claim-related figures can represent different concepts, such as estimated repair cost, replacement cost value, depreciation, deductibles, applicable valuation, or amounts associated with covered versus non-covered work. These distinct figures should not automatically be treated as interchangeable.
What May Happen After Filing
| Stage | What May Happen | What the Homeowner May Need to Review |
|---|---|---|
| Claim Acknowledgment | The claim may be recorded and assigned a reference number. | Review claim number and primary contact information. |
| Information Request | Additional documents or clarification may be requested. | Review what information is still outstanding or needed. |
| Inspection or Evaluation | The property may be inspected or otherwise evaluated. | Review which property areas and conditions were documented. |
| Estimate or Scope Development | A repair or replacement scope may be developed. | Review included roof areas, components, and work items. |
| Coverage or Valuation Communication | The insurer communicates information on policy evaluation. | Review applicable deductible, valuation method, and scope distinctions. |
| Payment or Repair Next Steps | The claim moves toward payment processing or repair planning. | Review communicated instructions and outstanding action items. |
An Inspection, Estimate, and Coverage Decision Are Different Things
Homeowners benefit from understanding that an inspection, an estimate, and a coverage decision serve completely different functions in the post-filing process:
1. Inspection: Focuses on what physical conditions were observed or documented on the property.
2. Estimate: Focuses on what repair or replacement work may cost based on the identified scope and pricing assumptions.
3. Coverage and Valuation: Focuses on how the policy applies to the reported loss and how the applicable claim value is determined.
Recognizing these distinctions helps prevent the assumption that a physical inspection alone automatically determines the final claim payment or coverage outcome.
Questions to Review During the Claim
Claim Number Assigned?
Has a reference number and contact info been provided for tracking?
Information Needed?
Are there any outstanding document requests from the insurer?
Areas Included?
Which specific roof sections and components are listed in the scope?
Deductible & Valuation?
What deductible and valuation assumptions apply to the figures?
Next Steps Clear?
What action items or communication steps follow next?
Keep a Running Claim Record
It can be useful to keep claim-related information organized in one place throughout the process. Maintain records of your claim number, insurer contact details, communication dates, inspection notes, estimates, photographs, receipts, correspondence, and notes regarding any outstanding requests. Good organization helps keep tracking simple.
What If New Damage Is Found?
Additional or previously undocumented damage may sometimes become apparent after the initial claim information is submitted or an inspection occurs. When new conditions are discovered, they may require additional documentation, clarification, or further evaluation depending on the claim circumstances. Providing clear records supports accurate ongoing review.
After the Claim Is Filed: What to Keep Track Of
Post-Filing Procedures Vary
The post-filing process, timing, documentation requirements, inspection protocols, estimate structures, and communication methods can vary widely by insurance company, policy language, geographic jurisdiction, and the specific circumstances of the loss. Reviewing your specific policy documents helps provide clarity tailored to your situation.
Key Takeaway
Filing a storm damage roof insurance claim initiates a multi-step process in which the reported damage is reviewed, documented, evaluated, estimated, and considered under the applicable policy provisions. Homeowners may receive requests for information and should review inspection findings, estimates, deductibles, valuation terms, and next steps carefully. Because the exact process varies by insurer and policy, understanding these general stages helps provide clarity without predicting a specific claim outcome.
Common Storm Damage Roof Insurance Claim Mistakes
Navigating a storm damage roof insurance claim involves coordinating multiple types of information, estimates, inspections, policy provisions, deductibles, and documentation. Avoidable mistakes often stem from incomplete information, unsupported assumptions, poor record organization, or confusion between physical roof damage and insurance coverage. Recognizing these pitfalls helps homeowners approach the process with greater clarity and organization. Making a mistake does not automatically determine a claim outcome, and insurance procedures, policy requirements, and claim circumstances vary considerably by insurer, policy language, and jurisdiction.
Most Claim Mistakes Start With Incomplete Information
Homeowners may sometimes begin the claim process without all relevant roof, property, storm, policy, or damage details readily available. Missing or inaccurate information can make it significantly harder to understand what an estimate includes, how policy terms apply, or what documentation may be needed during review.
Do Not Confuse Damage, Cost, and Coverage
It is essential to distinguish between what physically happened to the property during a storm, what repairs or replacement work may cost, and how the insurance policy addresses the reported loss. While closely related, these represent three completely different concepts that should not be used interchangeably.
Common Storm Damage Roof Insurance Claim Mistakes
Guessing Important Information
Guessing roof age, roof size, deductible amounts, storm date, or material type introduces inaccuracies. Use reliable records and identify information needing verification.
Assuming All Damage Is Storm-Related
Roofs often feature storm effects alongside age-related wear, maintenance issues, or prior conditions. The true cause and condition should be evaluated rather than assumed.
Assuming Damage Means Coverage
Visible physical damage and policy coverage are separate questions. The existence of physical damage does not automatically establish how a specific policy applies.
Focusing Only on Shingles
Storm effects can impact multiple roof components, such as flashing, ridge caps, vents, gutters, and roof edges, or related exterior areas.
Comparing Only Total Price
Two estimates can differ because of varying measurements, materials, labor assumptions, or scope. Understand what is included before comparing totals.
Losing Track of Records
Scattered photographs, estimates, receipts, emails, and notes make claim history hard to follow. Keeping organized records maintains clarity throughout.
Do Not Guess When the Information Can Be Verified
Important claim inputs—such as insurance deductibles, roof age, roof dimensions, roofing materials, dates of loss, damage descriptions, or previous repair records—should be based on reliable data whenever possible. If a particular detail remains unknown, it is far more effective to identify it as uncertain than to present an unverified guess as confirmed fact.
Other Mistakes That Can Complicate a Claim Review
Ignoring Related Property Damage
Focusing strictly on the roof surface while overlooking other affected property components like siding, windows, gutters, or ceilings.
Cleaning Up Before Documenting
Performing cleanup or temporary repairs without documenting visible conditions when it is safe and practical to do so.
Ignoring Estimate Scope Details
Relying on a total dollar amount without checking which specific roof areas, materials, components, and labor items are included.
Overlooking Roof Age & Condition
Failing to account for prior roof condition, wear, and age when evaluating property damage and replacement assumptions.
Confusing Depreciation & Deductibles
Treating depreciation (reduction in value) and deductibles (out-of-pocket policy amounts) as interchangeable concepts.
Failing to Track New Info
Failing to incorporate newly discovered photographs, measurements, or inspection findings as the claim record evolves.
Avoid Assumptions About What the Policy Covers
Policy language, endorsements, exclusions, deductibles, valuation methods, and claim circumstances fundamentally dictate how a reported loss is handled. Specific policy exclusions vary by carrier and contract, and coverage decisions depend entirely on the applicable policy and circumstances. Avoid assuming broad rules apply universally across different insurance providers.
Damage vs. Normal Wear
Roofs frequently exhibit both storm-related impact marks and ordinary aging or weathering. Distinguishing between storm damage and standard wear requires professional evaluation and careful inspection rather than surface-level assumption.
Estimate vs. Claim Value
An estimated repair cost or contractor bid is not necessarily equivalent to the final value associated with an insurance claim calculation, which is subject to policy valuation rules and deductibles.
Deductible vs. Depreciation
A deductible represents the policyholder's out-of-pocket portion under the policy, whereas depreciation measures physical wear and age reduction. These concepts serve distinct roles in claim figures.
What to Check Before Relying on Claim Information
| Potential Mistake | What Can Go Wrong | What to Verify |
|---|---|---|
| Incorrect Roof Size | Estimates and material calculations may be inaccurate. | Check professional roof measurements or blueprints. |
| Incorrect Roof Age | Valuation or depreciation calculations may misalign. | Review installation dates or historical property records. |
| Incorrect Roofing Material | Material quality or replacement matching can be wrong. | Identify exact shingle type, weight, and manufacturer. |
| Incorrect Deductible | Out-of-pocket financial expectations may be miscalculated. | Review the declarations page of your insurance policy. |
| Incomplete Damage Scope | Necessary repair components may be accidentally omitted. | Compare damage lists against all observable roof areas. |
| Missing Related Property Damage | Exterior or interior collateral damage gets overlooked. | Inspect siding, gutters, vents, and interior ceilings. |
| Different Estimate Assumptions | Comparing prices across bids becomes misleading. | Compare labor rates, disposal fees, and material scope. |
| Unclear Depreciation / Valuation | Actual cash value vs. replacement cost gets mixed up. | Check policy valuation terms and depreciation schedules. |
Compare the Details Before Comparing the Outcome
When reviewing claim documentation, estimates, or professional bids, it is exceptionally useful to compare underlying variables—such as roof measurements, affected areas, material quality, labor allocations, removal and disposal fees, depreciation, deductibles, and valuation assumptions. Examining the underlying details provides far more clarity and context than looking solely at a single bottom-line total.
Five Questions to Ask Yourself Before Using Claim Information
Is This Information Verified?
Check whether critical figures are backed by reliable documentation or are merely unconfirmed estimates.
What Is the Source?
Identify where the data came from—whether an insurance document, a professional inspection, or a general guess.
What Area Does This Cover?
Verify whether estimates or reports include the entire affected roof structure or only specific isolated slopes.
Are Damage and Coverage Separate?
Keep physical condition distinct from insurance policy applicability to maintain an objective perspective.
What Is Still Unknown?
Explicitly note any open questions or missing details that require further research or professional clarification.
Be Careful With Unverified Claim Assumptions
Homeowners should exercise caution when treating unverified statements, estimates, measurements, or assumptions as confirmed facts. Common examples include assuming a roof is a specific age without records, assuming every visible defect was caused by a single storm event, assuming an estimate includes every damaged accessory component, or assuming an initial inspection determines final coverage. Maintaining an objective, evidence-based approach helps prevent misunderstandings during the claim lifecycle.
Storm Damage Roof Insurance Claim Mistake-Prevention Checklist
What to Do Instead of Relying on Assumptions
Adopting a structured, methodical approach helps prevent common information-handling pitfalls. Follow these general practices:
1. Verify: Use reliable records, official policy documents, or available professional data.
2. Document: Record observable property conditions carefully with clear media.
3. Compare: Compare scope, line items, and underlying assumptions rather than totals alone.
4. Separate: Keep physical damage, repair cost, and policy coverage concepts distinct.
5. Track: Keep claim-related information well-organized as new information becomes available.
These steps represent general information-management practices designed to support clarity, rather than guarantees regarding claim outcomes.
Claim Requirements and Outcomes Vary
Insurance policies, insurance carriers, state jurisdictions, property conditions, storm characteristics, documentation standards, and claim circumstances vary widely. A mistake or oversight described in this section does not automatically determine whether a claim is covered, adjusted, or paid. Reviewing your specific policy contract provides the best guidance for your individual circumstances.
Key Takeaway
Many avoidable storm damage roof insurance claim problems arise from incomplete information, unsupported assumptions, unclear scope, poor record organization, or confusion between physical damage, repair cost, and policy coverage. Homeowners are encouraged to use reliable information, document observable conditions safely, understand what estimates include, and keep claim records thoroughly organized. These practices promote clarity and informed decision-making without determining coverage or guaranteeing a particular claim result.
Storm Damage Roof Insurance Claim Example
Exploring a hypothetical example can make it significantly easier to understand how roof damage scope, estimated repair or replacement cost, depreciation, deductibles, and valuation can interact during an insurance assessment. By walking through an illustrative scenario, homeowners can observe how individual components of an estimate connect without assuming that fictional numbers apply to their own unique property, policy terms, or insurer procedures. Actual insurance claims depend entirely on specific policy contracts, documented damage, and applicable state regulations.
Hypothetical Example — For Illustration Only
The following example uses fictional property and claim figures to demonstrate the general structure of a storm damage roof insurance estimate. These numbers are strictly illustrative and do not represent a universal formula, standard settlement, or prediction of what any insurer will pay. Actual claims vary substantially based on policy terms, coverage provisions, deductibles, valuation methods, depreciation rules, roof condition, damage scope, local pricing, insurer procedures, and claim circumstances.
Example Property (Hypothetical)
To provide a clear framework, this illustrative example assumes a hypothetical residential property profile:
Roof Area: 2,000 square feet
Roof Material: Architectural asphalt shingles
Roof Age: 8 years
Reported Event: Severe wind and hail storm
Damage Scope: Multiple roof areas with visible storm-related damage
Example Insurance Assumptions (Hypothetical)
This illustrative scenario applies fictional figures for calculation structure only:
Estimated Repair/Replacement Scope: $18,000
Example Deductible: $2,000
Example Depreciation: $4,000
Valuation Approach: RCV-style example with depreciation shown separately
Note: Actual policies may use different valuation methods and terms.
How the Hypothetical Claim Estimate Is Organized
In this simplified educational example, the figures flow through a structured calculation sequence to demonstrate how deductions and adjustments are applied:
This simplified example assumes the policy permits the depreciation shown to be recoverable after qualifying repair or replacement conditions are satisfied. Recoverable depreciation is not available under all policies. This total is an educational illustration only and does not represent a guaranteed insurance payment.
What Each Figure Represents
Estimated Repair Cost
Represents the hypothetical cost assigned to the example damage scope based on estimated labor and materials.
Depreciation
Represents a reduction applied under certain valuation approaches reflecting age, condition, or wear.
Illustrative ACV Amount
In this simplified example, estimated cost minus depreciation produces an illustrative amount before the deductible.
Deductible
The hypothetical deductible is subtracted in the example to show how out-of-pocket policy amounts affect totals.
Recoverable Depreciation
Demonstrates how some policies may allow certain withheld depreciation to be recovered under specified conditions.
Illustrative Final Amount
A hypothetical result after example assumptions are applied; it is not a guaranteed insurance payment or settlement offer.
Simple Example of the Calculation Flow
The relationship between the primary figures in this hypothetical example can be viewed through straightforward math and symbol flows:
$18,000 estimated scope − $4,000 example depreciation = $14,000 illustrative ACV-style amount
$14,000 − $2,000 example deductible = $12,000 illustrative amount after deductible
$12,000 + $4,000 example recoverable depreciation = $16,000 illustrative total after recoverable depreciation
This sequence is not a universal insurance formula. Different policies, endorsements, valuation methods (such as RCV vs. ACV), and insurer guidelines calculate claims through distinct contractual procedures.
Changes to the Damage Scope Can Change the Estimate
If the hypothetical damage scope were smaller or larger, the estimated repair or replacement cost would change accordingly. For example, a localized repair affecting only a single roof slope involves fewer materials and labor hours than a broader replacement scope covering multiple damaged sections. Altering the physical scope directly changes the starting figure in any estimate calculation.
Policy Terms Can Change the Claim-Related Amount
Deductible structures, valuation methods, depreciation treatment, coverage provisions, exclusions, endorsements, and other policy terms dictate how claim figures are calculated and presented. Two roofs with identical physical damage could yield different claim-related calculations under different insurance contracts or carrier guidelines.
How Different Hypothetical Scenarios Could Change the Example
Scenario A: Smaller Damage Scope
A smaller covered damage scope would produce a lower hypothetical repair or replacement estimate before policy adjustments, reducing both initial depreciation and subsequent calculations proportionally.
Scenario B: Same Damage, Different Deductible
Changing only the hypothetical deductible (for instance, using a higher percentage deductible) would alter the illustrative amount after the deductible, modifying the out-of-pocket financial relationship.
Scenario C: Different Valuation Method
A policy utilizing a different valuation approach could produce different claim-related figures or settlement structures even if the physical repair estimate remained identical.
Example Inputs and Their Potential Effect
| Example Input | Hypothetical Value | What It Can Affect |
|---|---|---|
| Roof area | 2,000 sq. ft. | Estimated scope and material quantities |
| Roof material | Architectural asphalt shingles | Material quality and labor assumptions |
| Roof age | 8 years | Potential depreciation assumptions |
| Estimated scope | $18,000 | Starting estimate in this example |
| Example depreciation | $4,000 | Illustrative ACV-style amount |
| Example deductible | $2,000 | Illustrative amount after deductible |
| Valuation approach | RCV-style example | Potential treatment of depreciation and recovery |
Why This Example Is Simplified
Real roof insurance claims involve considerably more variables than a clean, single-page example can capture. These variables include detailed roof measurements, complex roof geometry, multiple material types, localized labor rates, removal and disposal fees, accessory components (such as flashing, valleys, and vents), temporary emergency repairs, specific depreciation schedules, varying deductible types (flat vs. percentage), coverage limitations, policy exclusions, endorsements, and evolving inspection documentation.
This example intentionally simplifies these factors so readers can understand the basic relationship between major claim figures without getting overwhelmed by policy minutiae.
Variables That Can Change a Real Claim Estimate
Damage Scope
The extent and severity of storm-related defects across different roof slopes and components.
Roof Measurements
Total square footage, pitch, ridges, eaves, and valleys that dictate material quantities.
Roofing Material
Shingle type, grade, manufacturer specifications, and matching requirements.
Labor & Pricing
Regional labor rates, contractor overhead, and local market disposal fees.
Deductible
The specific flat dollar amount or percentage deductible stipulated in the policy contract.
Valuation Rules
Carrier guidelines governing depreciation calculation methods and recovery rules.
Hypothetical Example vs. Real Insurance Claim
Hypothetical Example
- Fixed assumptions and controlled variables
- Simplified round numbers for clarity
- Straightforward, predictable calculation flow
- Purely educational and illustrative purpose
Real Insurance Claim
- Actual policy terms, endorsements, and exclusions
- Actual damage scope evaluated by adjusters
- Precise property measurements and local pricing
- Insurer-specific review procedures and documentation
The hypothetical example cannot determine or predict the outcome of a real insurance claim.
What a Storm Damage Roof Insurance Claim Calculator Can Help Illustrate
A storm damage roof insurance claim calculator can help users organize hypothetical inputs—such as roof size, estimated repair or replacement cost, depreciation, deductibles, valuation assumptions, and other user-entered variables—to understand how these figures connect mathematically.
Calculator results are estimates based exclusively on the inputs and assumptions provided by the user. A calculator does not determine policy coverage, guarantee claim approval, establish an insurer's final valuation, replace an insurance contract, or predict an actual claim payment.
Before Using a Claim Estimate Example for Your Own Situation
Insurance Claim Calculations Are Policy-Specific
The numerical example provided in this section is intentionally simplified for educational clarity. Actual claim calculations depend entirely on the applicable policy contract, valuation method, deductible provisions, damage scope, supporting documentation, insurer procedures, and other individual circumstances. The example does not represent a standard settlement or universal insurance formula.
Key Takeaway
A storm damage roof insurance claim estimate involves several separate figures, including the repair or replacement scope, depreciation, deductible, and valuation method. A hypothetical example can clearly illustrate how those numbers interact, but the result of an actual claim depends on the applicable policy and documented circumstances. Homeowners are encouraged to treat calculator outputs and educational examples as estimates based on entered assumptions rather than as predictions of what an insurer will pay.
Frequently Asked Questions
Navigating a storm damage roof insurance claim involves understanding deductibles, depreciation, policy limits, and documentation. Use this comprehensive FAQ guide alongside our Storm Damage Roof Insurance Claim Calculator to estimate your payout and optimize your insurance claim.
No matching questions found
Try searching using different keywords like "deductible", "ACV", "RCV", or "wind damage".
A storm damage roof insurance claim is a formal request filed with your insurance provider to cover the costs of repairing or replacing your roof following severe weather events like hail, wind, hurricanes, or severe thunderstorms.
A roof insurance claim calculator works by taking inputs such as your total roof square footage, estimated replacement cost per square, age of the roof, depreciation rates, and your policy deductible to estimate your out-of-pocket costs and insurance payout.
Actual Cash Value (ACV) pays out the depreciated value of your roof based on its age and wear, whereas Replacement Cost Value (RCV) covers the full cost to repair or replace your roof with materials of like kind and quality without deduction for depreciation.
Roof depreciation is typically calculated by dividing the current age of your roof by its estimated total useful lifespan (e.g., 20 or 25 years) to find the percentage of wear, which is then multiplied by the replacement cost to determine total depreciation.
A roof insurance deductible is the predetermined out-of-pocket amount you must pay toward your roof repair or replacement before your insurance coverage kicks in. Deductibles can be a flat dollar amount or a percentage of your home's insured value.
A percentage deductible (often 1% to 5%) is calculated as a percentage of your home's total insured structural value (dwelling coverage). For example, a 2% deductible on a home insured for $300,000 means you pay the first $6,000 of damage.
Filing a claim involves getting a professional roof inspection, documenting the damage with photos and videos, contacting your insurance company to open a claim, meeting the insurance adjuster onsite, and reviewing the settlement offer.
The time limit to file a roof damage claim varies by state laws and insurance policy contracts, ranging typically from 1 year to 2 years from the date the storm occurred. Review your specific policy or consult your provider immediately after a storm.
Weather-related roof damage is typically classified as an "act of God" or non-forced claim. While individual rate hikes depend on state regulations and overall regional storm activity, insurers often raise rates across entire geographic areas rather than penalizing a single policyholder.
Most standard homeowners policies cover roof damage caused by high winds, hail, fallen trees, lightning strikes, and heavy snow or ice buildup. Gradual wear and tear or lack of maintenance are generally excluded from coverage.
If your claim is denied, you can request a detailed explanation in writing, hire an independent roof inspector or public adjuster for a second opinion, gather additional weather data or evidence, and file a formal appeal or request re-inspection.
Payouts are often split into multiple checks: an initial ACV check (minus your deductible) given after the adjuster's estimate, and a depreciation check released after the contractor completes the repairs and submits proof of completion.
Building code upgrade coverage (or ordinance and law coverage) pays for extra expenses required to bring your roof up to current local building codes during repairs, such as installing proper decking or ice and water shields that older roofs lacked.
Insurance covers a full roof replacement if the damage is widespread across multiple slopes, if matching shingles are no longer manufactured, or if local building codes prohibit patching over damaged sections.
Yes, you have the legal right to select any licensed and insured roofing contractor of your choice to perform the repairs, rather than being forced to use a contractor recommended by your insurance company.
A public adjuster is a licensed insurance professional who advocates on your behalf rather than the insurance company's. You might hire one if your claim is significantly undervalued, disputed, or wrongfully denied.
Our Trusted Sources
Our storm damage roof insurance claim calculations, payout estimation models, deductible guidelines, and policy standards are built upon verified insights from leading government agencies, insurance advisory organizations, and independent safety codes.
Accurate storm damage estimates, insurance claim payout forecasts, and deductible calculations rely heavily on standardized metrics like policy provisions, wind resistance ratings, and proper documentation protocols[cite: 2]. By aligning our calculator tools with recognized insurance guidelines and building codes, we ensure that the financial and practical insights provided match real-world insurance claim workflows and policy considerations[cite: 2].
Related Calculators
Discover our suite of additional roofing and estimation tools designed to help you analyze repair costs, compare replacement options, calculate material quantities, and manage your project budget effectively.
Whether you are filing an insurance claim after a severe storm, pricing material bundles, or deciding between targeted repairs and a full overhaul, our interactive calculator tools provide reliable estimates to help you make informed decisions and budget with confidence.